5 SEC Deregulatory Shifts in September That Could Change the Investment Game Forever—Are You Ready?
Ah, September—a month famous for crisp air, pumpkin spice lattes flooding our hands, and the crowd-pleasing kickoff of football season. It’s the time when the SEC usually ramps up its enforcement blitz, dropping new actions like autumn leaves. But hold up—this year, something’s flipped. Instead of piling on restrictions, the SEC’s actually rolling back some long-standing rules. Yep, they’re rolling out proposals to reshape everything from shareholder proposals to tokenized stock trading, seemingly rewriting decades of regulatory playbooks. It’s like watching your favorite fall ritual take an unexpected twist—kinda like realizing your pumpkin spice latte has a secret shot of espresso. So, what does this mean for public companies, investment pros, and governance nerds? Buckle up—because the SEC’s shifting gears might just reshape the landscape more than you think. Ready to deep dive into what’s on the chopping block and what could be brewing next? LEARN MORE
When the morning air gets brisk and the calendar turns to September, we can rely on certain rites of fall: pumpkin spice anything, football season, and a flurry of enforcement activity at the SEC. But this year, something’s different. Instead of dropping enforcement actions like so many tree leaves, the SEC is going in the other direction and pulling rules off the books. This month alone, it has proposed to:
- Rescind Rule 14a-8
On September 16, the Commission proposed to rescind Rule 14a-8 in its entirety, ending an 85-year-long federal role in the shareholder proposal process. The agency release argues the rule exceeds the SEC’s authority and intrudes on state corporate law without authorization from Congress. You could see this one coming. Chair Paul Atkins questioned the rule’s premise in an October 2025 speech; a December 2025 executive order directed him to consider rescinding it; and Corp Fin stopped responding to 14a-8 no-action requests in August. States could fill the gap with their own standards, or companies could write inclusion requirements into their own charters and bylaws, to the extent permitted by state law.
- Modernize the Proxy Solicitation Process
The same day, in a separate document running 152 pages, the SEC proposed a proxy reform package. Companies would no longer have to deliver an annual report to stockholders. The package would eliminate the delivery deadline for documents incorporated by reference into a proxy statement, as well as the ability to submit notices of exempt solicitation, while dropping the minimum broker search period from 20 business days to five. As a headline on Cooley’s Governance Beat put it, “It’s a Biggie!”
The 14a-8 release also amends Rule 14a-4(c), expanding when a company may vote the proxies it receives on proposals raised at a meeting but absent from its proxy card.
- Rescind the Pay-to-Play Rule
On September 3, the SEC proposed to rescind Rule 206(4)-5, which bars an investment adviser from advising a pension fund or other government client for two years after the adviser contributes to an official who can influence the selection of the investment advisor. The SEC describes as a strict-liability regime, under which small donations or “foot faults” trigger substantial prohibitions and fines.
- Modernize Transfer Agent Rules
The September 1 proposal is the first substantive rewrite of the transfer agent rules since the late 1970s, and this one cuts both ways. It would permit the master securityholder file to be maintained using various technologies, including a blockchain, but impose the industry’s first mandatory board-approved compliance program as well as gatekeeping duties on restrictive legends. Comments close November 3.
- Open a Limited Path for Tokenized Stock Trading
On September 17, the SEC issued the Innovation Exemption, a five-year order allowing approved platforms to trade blockchain versions of NMS stock without registering as exchanges. Trading runs through screened liquidity pools rather than a conventional order book, and a companion exemption keeps the firms supplying that liquidity from being treated as dealers. Two conditions have drawn the most attention: token holders must keep the rights they would have holding the stock outright, and a company can block a third party from tokenizing its shares, with written notice, a 30-day wait, and a veto if it objects in time.
The order came two days after the Senate’s cloture vote on the Clarity Act failed 49-50.
Taken together, September’s actions point toward a broader SEC effort to reconsider longstanding rules while creating more flexibility for emerging market practices and technologies. Most of these changes are not final, and the Innovation Exemption is temporary and conditional, so their ultimate impact will depend on final rulemaking, public comments and how market participants respond.
For public companies, investment advisors, transfer agents, and governance teams, the practical takeaway is not simply that regulation is being reduced. The rules governing shareholder proposals, proxy solicitation, political contributions, securities recordkeeping, and tokenized trading could all look materially different in the coming years. Companies should be tracking the proposals now, assessing which existing policies and processes could be affected and preparing to adjust if the Commission ultimately adopts the changes.
All five September actions are proposals or a temporary order, with comment periods running 60 days. That leaves plenty of time to think them over while sipping your pumpkin spice latte.
—
Don’t just read about the trends. Leverage them. Explore Intelligize with a free trial.
Selene Dog Water Fountain, 4L Stainless Steel Dog Water Fountain with Visual Water Level, Super Quiet Dog Water Bowl, 5-Stage Filtration Pet Water Dispenser, Easy to Clean - 4L
$86.99 (as of September 23, 2026 03:11 GMT +00:00 - More infoProduct prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on [relevant Amazon Site(s), as applicable] at the time of purchase will apply to the purchase of this product.)
Roku 40-Inch Select Series Smart TV 2026-1080p Full HD TV - RokuTV | Flat Screen LED Television with Voice Remote, Wi-Fi & Bluetooth Headphone Mode - Streaming Live Local News Sports & Movies
$158.00 (as of September 23, 2026 03:30 GMT +00:00 - More infoProduct prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on [relevant Amazon Site(s), as applicable] at the time of purchase will apply to the purchase of this product.)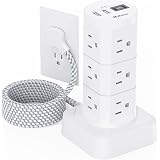
Power Strips with Surge Protection, Flat Plug Power Strip Tower | Charging Station 12 Outlets 4 USB Ports, 1080J 6Ft Extension Cord with Multiple Outlets, Office Supplies, Dorm Essentials
$19.97 (as of September 23, 2026 03:30 GMT +00:00 - More infoProduct prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on [relevant Amazon Site(s), as applicable] at the time of purchase will apply to the purchase of this product.)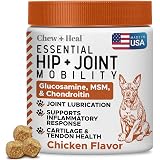
Hip and Joint Supplement For Dogs, 60 Soft Chews, Glucosamine & Chondroitin | MSM, Vitamin E & C -Small & Large Dog Breeds - Puppy & Senior Mobility Support, Cartilage & Joint Lubrication & Health, Pain
$8.99 (as of September 23, 2026 03:11 GMT +00:00 - More infoProduct prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on [relevant Amazon Site(s), as applicable] at the time of purchase will apply to the purchase of this product.)

Post Comment