
State Pension Shakeup: Why Your Retirement Income Could Break Free—and What It Means for Your Future Cash Flow
Is the pension triple-lock really about to get a makeover? It seems the quiet nods in last weekend’s comments section were louder than any outcry could have been—a rare moment when everyone seems to agree that the old system’s generosity might just be heading for its limits. With the Prime Minister stepping up to “pull the bandaid off,” Andy Burnham’s proposal to tweak the triple lock aims squarely at easing the long-term financial strain while funneling savings into one of the UK’s toughest challenges: social care for the elderly. But here’s the kicker—can we truly balance fairness with fiscal responsibility, or are we just rearranging deck chairs on a ship that’s sailing into choppier waters? In this breakdown, we’ll explore why today’s pension promise might be a smart squeeze of the past’s excess, and what that means for all of us, whether we’re eyeing retirement or still grinding away. Ready to dive into the triple lock’s new twist? LEARN MORE
The first Weekend Reading every month can be read by anyone on the Monevator website. Subscribe for free to our email newsletter or become a member to ensure you see the rest.
I thought it notable there wasn’t more pushback in the comments last weekend, when I cited a growing consensus that something must be done about the pension triple-lock.
A few of you raised thoughtful questions, mostly about what really drove the convergence of pension-age income with that of the rest of the population.
But there were no pitchforks, no curses. No shaking a fist at the unfairness of it all.
With hindsight, this eerie quiet further suggested that most of us can see the pension triple-lock is fair game – unsustainable in its current form.
And sure enough, on Tuesday the Prime Minister pulled the bandaid off.
The triple lock would be tweaked to reduce its long-run cost, Andy Burnham said, and any savings used to fund later life social care.
Triple-topped
As the BBC recaps:
The triple lock was introduced in 2010 by the coalition government and designed to ensure the value of the state pension was not overtaken by the increase in the cost of living or the incomes of working people.
It means the state pension rates rise every April by either inflation, earnings growth or 2.5% – whichever is the highest.
Burnham said this will stay in place until 2030, at which point he would like to “adjust it”.
He said: “The state pension will continue to rise every year at least by prices or 2.5%. And it will hold its value relative to earnings over time so that pensioners will always share in the rising prosperity of the nation.
But this change will generate significant savings which we will use to build up our national care service.
Some may not realise it but older people with nothing more than the state pension, or only a little more, can find themselves paying care charges today from that small income. Under my plan, this will no longer happen.”
On first blush it looks a sensible compromise. I think most people support a reasonable State Pension, if only because we’ll benefit from it ourselves.
But its ‘every way’s a winner’ ratchet made the old triple-lock system increasingly unviable. It’s already forecast to cost around three times as much by the end of the decade as originally expected.
Burnham’s tweak should reset the built-in escalation. According to the IFS:
The new, reformed version of the triple lock still contains three parts.
Inflation, earnings growth and 2.5% are all important.
But the new mechanism means that each year the state pension will instead increase by the maximum of:
- CPI inflation
- 2.5%
- the amount needed to ensure the state pension keeps up with average earnings growth since the introduction of the new policy.
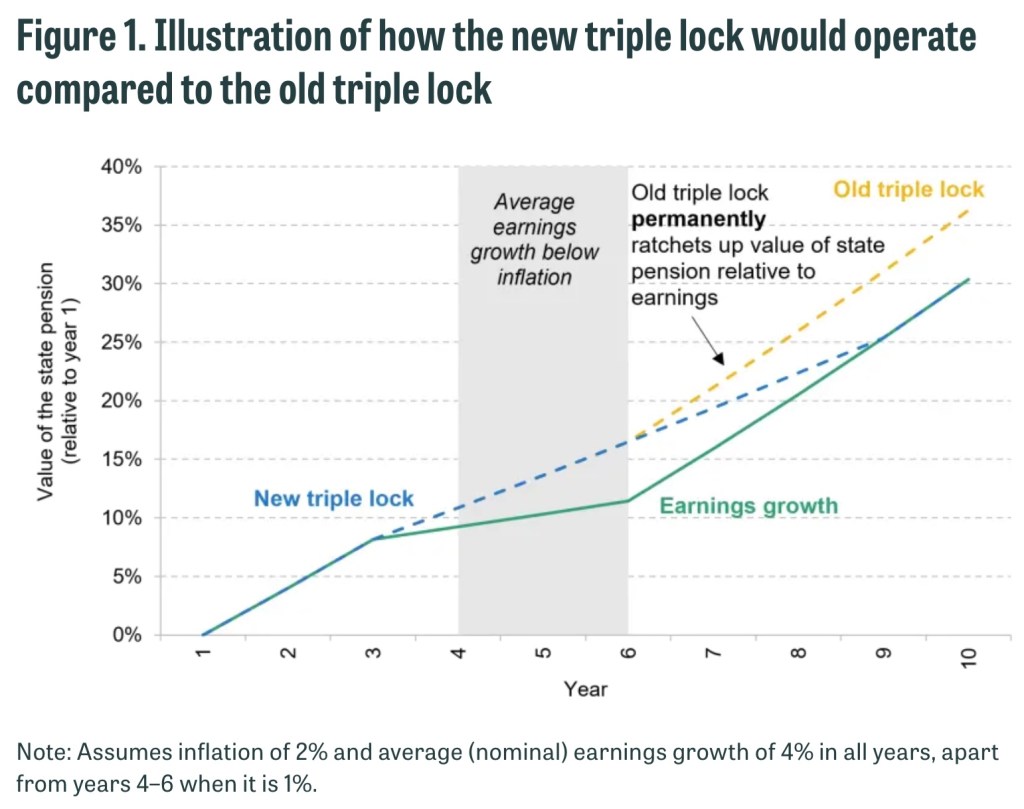
Essentially Burnham is saying enough is enough on the catch-up we saw last week. The new tweak effectively cements the status quo, relative to average earnings, in the long run, while still providing protection against everyday inflation.
Here’s an illustrative scenario:

Source: IFS
Sense and sensibility
At first blush it looks like a good change to me.
The old mechanism was becoming too expensive. This new triple-lock will still protect the real value of the State Pension – and it will still be increasingly costly to fund. But the revised link with average earnings at least ties that cost implicitly to the taxes that will pay for it.
The tweak also seems like a pragmatic one – announced without bombast, a sensible timeline to delivery, and made in the face of some political risk.
Finally, funding social care for the elderly is a huge issue, as anyone who worked through my co-blogger’s deep dive a few years ago knows.
I don’t like the means-testy sounding way that Burnham is pitching his fresh look at the issue. Ideally I’d prefer some kind of paid-in insurance system that meant everyone would get to live in a care home for free in the end if they needed to. This would remove the lottery element to end-of-life planning, making it much easier to save (and spend) accordingly.
But at least it’s a real and weighty problem to tackle, unlike the phoney wars of the past decade.
Obviously it’s too early to declare that UK politics has returned to a reasonable centre ground. But might this too be a tweak in the right direction?
Have a great weekend!
From Monevator
Our updated guide to help you find the best broker – Monevator
Their first home: the next buying opportunity? – Monevator [Mogul Members]
From the archive-ator: FIRE-side chat: domestic geo-arbitrage made it possible – Monevator
News
Relaunch of Help to Buy with new Your First Home scheme – This Is Money
Crackdown announced on ‘cowboy’ leasehold property agents – BBC
UK borrowing costs up as gilt yields hit 6% for first time since 1998 – Independent
Average homeowner mortgage rate doubles to 4% for first time since 2009… – T.I.M
…but house prices are the most affordable since 2015 – This Is Money
UK disposable income rises as benefits payouts soar ahead of wages – City AM
Jaecoo 7 UK’s best-selling car as Chinese brands take nearly 25% of market – Autocar
TPG joins race for Monzo stake after end of £10bn bid talks – Sky
Barclays softens return-to-office plans for UK staff after backlash – Guardian
London’s Oxford Street to be pedestrianised from October – BBC
UK diesel price hits record of £2 a litre – Guardian

EVs up to nine times cheaper to drive than petrol cars in UK – Carbon Brief
Products and services
Disclosure: Links to platforms may be affiliate links, where we may earn a commission via a tracking cookie. This article is not personal financial advice. When investing, your capital is at risk and you may get back less than invested. With commission-free brokers other fees may apply. See terms and fees. Past performance doesn’t guarantee future results.
Three major lenders lift mortgage rates as sub-5% deals disappear fast – This Is Money
Barclays switch offer: Get up to £300 – Be Clever With Your Cash
Get up to £1,500 cashback when you transfer your cash and/or investments to Charles Stanley Direct through this affiliate link*. Terms apply – Charles Stanley*
The zero-bills home: how one family is beating the energy price hikes – Guardian
Dine at Michelin-starred restaurants across the UK for as little as £20 – Which
Get up to £3,000 cashback when you open an Interactive Investor SIPP via this affiliate link*. Terms apply – Interactive Investor*
Is Amazon Prime worth the money? – Be Clever With Your Cash
Seven things to know before taking advantage of Free Wills Month – Which
Homes for sale in landmark towers, in pictures – Guardian
Comment and opinion
Index investors probably aren’t missing much in private markets – A.W.O.C.S.
Ten ways to feel rich – White Coat Investor
People are too worried about the bond market – Fortunes & Frictions
A brutal bond market [US but relevant] – A Wealth of Common Sense
Financial lessons – Humble Dollar
FIRE makes taking on more debt a non-starter – Financial Samurai
Exponential wealth: centuries of stock and bond returns – CFA Institute
Five things worth paying for – Dan Haylett
Stop obsessing about the safe withdrawal rate… – Use Your Wealth
…though here’s yet another way to improve on it if you do [Research] – SSRN
More recent academic research – Alpha in Academia
On the job mini-special
Work hard – and be less precious – when you’re young – Slow Boring
What’s eating the office? – Dror Poleg
The invisible way companies are using AI to set salaries – W.S.J. [h/t Abnormal Returns]
Naughty corner: Active antics
Steps to take if you own a lot of stock in your employer – The Joint Account
What makes Warren Buffett unique – Jason Zweig
Shopify, the snowboard shop that redefined e-commerce – Fiscal.AI
The looming AI earnings and accounting headwind – Tker
Most stocks are losers – A Wealth of Common Sense
AI is boosting interest rates, not inflation – Morningstar
Anthropic’s S-1 pre-IPO filing mini-special
The numbers behind Anthropic: an FAQ – The Ringer
Anticipating the risk factors in Anthropic’s prospectus – Shivaram
Kindle book bargains
The Man Who Solved the Market by Gregory Zuckerman – £0.99 on Kindle*
Money: The Story of Humanity by David McWilliams – £0.99 on Kindle*
The Price of Money by Rob Dix – £0.99 on Kindle*
Risk and Reward by Ben Carlson – £0.99 on Kindle*
Environmental factors
Heat pump sales soar across Europe after states cut electricity taxes – Guardian
The US state replacing power plants with home batteries – BBC
Wolves did not save Yellowstone – The Conversation
A conservation success story for New Zealand’s heaviest insect – Phys.org
Racing to save the Florida orange industry from collapse – WSJ [h/t Abnormal Returns]
Robot overlord roundup
Where’s the ‘intelligence explosion’? – Ramez Naam via Noahpinion
How Anthropic and OpenAI got serious about business models in 2026 – Tom Tunguz
Apps, agents, and aggregation – Stratechery
More words that explain AI – Dror Poleg
A critique of Ed Zitron’s AI prediction track record – Dan Luu
AI risks and you mini-special
Will AI agents cause the next corporate bank run? – Treasury Spring
Why many people fear AI will ruin their retirement… – Mr Money Mustache
…and why many people don’t fear AI enough – Behavioural Investment
Not at the dinner table
Brexit referendum ‘possible’ in Labour election manifesto, says Burnham – BBC
US-China trade is unravelling as American’s deficit shifts to other partners – Econovis
The US “Who You Gonna Believe?” election – Paul Krugman
Off our beat
Random is as random does – Tim Harford
A brief history of the Bloomberg terminal – IEEE
The 12th-century military disaster that forever changed global finance – Big Think
Treat your to-read pile like a river, not a bucket – Oliver Burkeman
How Japan’s geography determined its history – Uncharted Territories
Men are having a purpose crisis, and things are getting weird – Next Big Idea
People who walk more or walk faster live longer, study finds – Harvard Medical School
M&S Custard Cream Spread: Britain has completed food – Central Bylines
And finally…
“A world equity index tracker is the only equity investment a rational investor ever needs to own.”
– Lars Kroijer, Investing Demystified*
*Links marked with an asterisk are affiliate links.

Banana Bunch (4-5 Count)
(as of October 3, 2026 03:06 GMT +00:00 - More infoProduct prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on [relevant Amazon Site(s), as applicable] at the time of purchase will apply to the purchase of this product.)
SUPERDANNY 10Ft Extension Cord with Multiple Outlets, Flat Plug Power Strip | 2100J, 13AC 2 USB C 2 USB A Charging Ports, Surge Protector, Desk Charging Station, Home Office, College Dorm Room Essentials
$15.99 (as of October 3, 2026 03:26 GMT +00:00 - More infoProduct prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on [relevant Amazon Site(s), as applicable] at the time of purchase will apply to the purchase of this product.)
Amazon Fire TV Stick HD (newest model), free & live TV, Alexa Voice Remote, powered by the TV, effortless setup, find shows faster with Alexa+
$15.99 (as of October 3, 2026 03:17 GMT +00:00 - More infoProduct prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on [relevant Amazon Site(s), as applicable] at the time of purchase will apply to the purchase of this product.)
Blink Outdoor XR+ and Battery Doorbell 2K+ — Extended range wireless Outdoor 4 camera and 2K battery doorbell. Sync Module XR+ included — 2 camera system + doorbell
$69.99 (as of October 3, 2026 03:26 GMT +00:00 - More infoProduct prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on [relevant Amazon Site(s), as applicable] at the time of purchase will apply to the purchase of this product.)

Post Comment