
Unlocking the Secret Strategy Behind Pension Plans That Could Change Your Financial Future Forever
Ever wondered if getting thousands of folks to opt into a pension scheme without the usual fuss is even possible? Turns out, Ireland’s new auto-enrolment plan, MyFutureFund, launched this year, is shaking up the game in a way that’s hard to ignore. With pension ownership jumping by a solid 17% since 2025, and over 835,000 participants already on board contributing more than half a billion euros, this scheme is proving to be more than just a fancy idea. What’s really surprising is the exceptionally low opt-out rate—less than 4%—when experts predicted it could be two to four times higher. That tells me there’s a growing awareness and commitment to retirement savings, even amidst today’s tough economic backdrop. But while the state’s straightforward top-up for every €3 contributed makes saving almost painless, it does beg the question: are folks missing out on some of the perks bigger pension schemes offer? As the scheme cruises forward, maintaining this momentum will be no small feat, especially with contribution hikes looming in 2029. So, is MyFutureFund the wake-up call younger workers needed to finally take charge of their financial futures? Let’s dive deeper. LEARN MORE
So far, MyFutureFund is being hailed as a success in terms of increasing pension coverage and raising awareness of retirement saving, writes Sorcha Corcoran
Research from the Competition and Consumer Protection Commission, published in September, reveals that pension ownership has risen by 17 per cent since 2025.
The introduction of MyFutureFund, Ireland’s new auto-enrolment scheme, on January 1 has been identified as a key factor that contributed to this increase.
According to the National Automatic Enrolment Retirement Savings Authority (NAERSA), MyFutureFund now has over 835,000 participants and over €500m in contributions has been collected and invested on their behalf.
During the first opt-out window, between July 1 and August 31, 29,000 eligible participants submitted a request to opt out of MyFutureFund.
At less than 4 per cent, this represents an opt-out rate that is much lower than expected. Estimates had ranged from 10 per cent to 16 per cent.
In addition, more than 10,500 workers have voluntarily opted in to MyFutureFund.
“While future economic headwinds could change this, the current, extremely low opt-out rate is particularly encouraging,” Niall Fitzgerald, head of retirement solutions at Zurich Ireland, says.
“The seamless launch, with deductions and investments proceeding without issues, has helped build confidence in the system.”
Olive Reid, head of account management, corporate pensions, at New Ireland, says the low opt-out rate against a challenging cost-of-living backdrop indicates support by employees for long-term saving.
“The requirement for employees to remain enrolled for six months also gave employees and employers time to adjust to deductions and allowed members to see their own pension fund begin to build,” she adds.
Maintaining the low opt-out achieved so far with MyFutureFund will be challenging, particularly when contribution rates increase in January 2029 and every three years thereafter, Fitzgerald warns.
“It’s therefore essential that the NAERSA clearly communicates the benefits of retirement saving to existing contributors well in advance of these increases to encourage members to remain within the system,” he says.
“Overall, the introduction of auto-enrolment in Ireland has increased awareness, particularly among younger workers, of the need to take personal responsibility for saving adequately to maintain a good standard of living in retirement.”
In many cases, Fitzgerald adds, MyFutureFund has prompted employees to join their own occupational pension scheme or open a Personal Retirement Savings Account (PRSA) earlier than they might otherwise have done.
Another key advantage is the simple and transparent state top-up: for every €3 an employee contributes, the state adds €1.
However, this simplicity means MyFutureFund doesn’t offer some of the benefits available through occupational pension schemes or PRSAs.
“Higher-rate tax relief is often more generous than the State top up. There is also greater flexibility in occupational schemes and PRSAs, including the ability to make additional employee contributions or Additional Voluntary Contributions, which isn’t currently possible within MyFutureFund,” Fitzgerald explains.
Glenn Gaughran, head of business development at Independent Trustee Company, says for those employers deciding between a master trust and a PRSA, it’s important to assess which pension scheme offers the best value and is most appropriate for your employees.

“Be sure too to seek impartial advice so you understand how the schemes differ and how they compare on costs,” he says.
“The likes of these costs, when employees plan to retire, what they want to invest in, and what is in the best interests of pension members will help you decide which pension product will suit your company and employees best.”

Propel, Kiwi Strawberry, Zero Calorie Sports Drinking Water with Electrolytes and Vitamins C&E, 16.9 Fl Oz (12 Count)
$9.97 (as of October 31, 2026 03:14 GMT +00:00 - More infoProduct prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on [relevant Amazon Site(s), as applicable] at the time of purchase will apply to the purchase of this product.)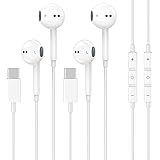
2 Pack [Apple MFi Certified] USB C Headphones Wired for iPhone 18 17 16 15 | Wired Earbuds with Microphone & Remote Control Noise Cancelling Type C Earphones for iPhone Duo 18 17 16 15 Pro Max, Galaxy
$13.99 (as of October 31, 2026 03:34 GMT +00:00 - More infoProduct prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on [relevant Amazon Site(s), as applicable] at the time of purchase will apply to the purchase of this product.)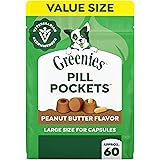
Greenies Pill Pockets Large Size Dog Treats, Peanut Butter, 15.8 oz | Vet-recommended, masks pill smell & taste, moldable texture, capsule size, natural ingredients, no fillers, 15.8 oz. pouch
$19.96 (as of October 31, 2026 03:14 GMT +00:00 - More infoProduct prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on [relevant Amazon Site(s), as applicable] at the time of purchase will apply to the purchase of this product.)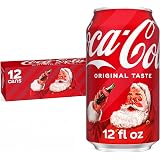
Coca-Cola Soda Soft Drink Fridge Pack Cans, 12 fl oz, 12 Pack | Carbonated drink with classic cola flavor
$7.68 (as of October 31, 2026 03:14 GMT +00:00 - More infoProduct prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on [relevant Amazon Site(s), as applicable] at the time of purchase will apply to the purchase of this product.)


Post Comment