
I Sold Most of My 15–21% Payout Stock Years Ago—Then It Exploded 110% in One Day. Here’s What I Wish I Knew Beforehand.
On November 11, 2026, Tong Hsing dropped a bombshell: an offer to buy Singapore Exchange-listed Global Testing for S$2.30 a share in cold, hard cash. The market reacted like a shot in the arm — Global Testing shares skyrocketed about 110% in a single day. Funny thing is, I didn’t even catch the surge until Standard Chartered, my broker, pinged me about some corporate action paperwork. Meanwhile, my investing circle was buzzing with money bag GIFs, leaving me both shocked and intrigued. Why was I so out of sync? Well, I only held 50 shares — a modest position compared to my past stakes since 2015. This company has danced in and out of my portfolio over the years, and plenty have already shared their tales. So, here I am, keeping it simple: laying down my numbers, my dates, and the story behind why Global Testing caught my eye — and why I eventually bid it adieu. Ready to dive into the ups, downs, and surprises of a small but fascinating chip-testing firm? Let’s get to it. LEARN MORE
img#mv-trellis-img-1::before{padding-top:127.04714640199%; }img#mv-trellis-img-1{display:block;}img#mv-trellis-img-2::before{padding-top:95.5078125%; }img#mv-trellis-img-2{display:block;}img#mv-trellis-img-3::before{padding-top:62.20703125%; }img#mv-trellis-img-3{display:block;}img#mv-trellis-img-4::before{padding-top:62.20703125%; }img#mv-trellis-img-4{display:block;}img#mv-trellis-img-5::before{padding-top:62.20703125%; }img#mv-trellis-img-5{display:block;}
On 11 November 2026, Tong Hsing offered to buy SGX listed Global Testing for S$2.30 a share in cash.
Global Testing shares jumped about 110% in a day.
I didn’t even realise the price moved so much and only got to know about this when my broker Standard Chartered inform me about corporate action that needs to be done.
Some of my close investing friends was posting money bag GIFs and I got a shock its so much.
Global Testing is in Daedalus Income portfolio. So why wasn’t I able to feel the difference?
That’s because I own very little of it now. Just 50 shares. But Global Testing has been part of my portfolio on and off since 2015, and a lot of people have already shared their own stories about this stock.
So this post is simpler. I want to put my numbers and dates down in one place, so everyone can see them clearly.
Why I own what I own, and what happened
I first bought in May 2015, about S$6,900 worth, when the stock was priced at S$0.14.
When I first bought this, I liked it because it was a company with net cash, and I thought it was sitting at a decent value point. It was always trading at about a 10% dividend yield. When I looked at the business, I felt the earnings could cover the dividends.
That said, I can’t claim I knew a lot about it.
Back then, you really couldn’t find much information. All I knew was that it was a testing firm operating in Taiwan, and that’s all. Because of that, I never put a big chunk of my capital into it. I mainly wanted to watch it play out over time, and I figured I’d collect some dividends along the way. I also paid attention to how the company handled dividends and, at times, capital reductions.
In the end, I decided to sell. The main reason was that it’s a very illiquid counter. Most days, it felt like I was the only one buying, and if I wasn’t, there wouldn’t be much trading at all. So I always worried that if the company announced a poor dividend, the price would drop, and I wouldn’t be able to get out in time. Because of that, I decided I was done with this company.
What does Global Testing (Ticker AYN) do?
Global Testing tests computer chips for other companies.
A wafer is a thin slice of silicon with many chips printed on it. Before those chips end up in a phone or a car, someone has to check that each one works. That’s the job. Global Testing doesn’t design chips. It’s the quality check station.
Global Testing does wafer sorting and final testing, mostly for chips used in consumer electronics and communication devices, and more recently for cars.
The head office and factory are in the Hsinchu industrial park in Taiwan. The main customer markets are Japan, Taiwan and Singapore. It has been listed on the Singapore Exchange since 24 August 2005.
Global Testing… is a very Small firm
Just before the offer, the market valued the whole company at about S$34 million.
- Revenue: about US$46 million in 2025.
- Net profit: about US$3.9 million in 2025.
- People: one data site puts the headcount at 567.
- Shareholders: about 2,500, with just over half of the shares in public hands.
I would have reckon the subsidiary where some of you work at moved more money than this.
Who owns Global Testing
As of March 2024:
- Yageo group: about 29% (23.64% directly and 5.28% through Kuo Shin Investment).
- Chen Tie-Min: 10.87%.
- Chia Soon Loi: 7.25%.
Mr Chen is a Senior Executive Director of Global Testing. He is also the chairman of Yageo and of Tong Hsing, the company now making the offer.
16 years of Global Testing Earnings
A short history of its revenue and earnings from 2015 to 2026
- May 2015. Every 20 old shares became one. The company also paid S$0.075 per old share, which worked out to about S$1.50 per new share and about US$40 million in total.
- 2016 to 2017. A payout of about S$0.20 a share each year, a mix of capital reductions and dividends.
- 2018. Revenue fell 18.9% to US$22.8 million because customers placed fewer orders. A profit turned into a loss of about US$5.0 million. No dividend was recommended.
- 2019. Another loss, of US$3.3 million.
- 2020. Covid hit. The share price touched S$0.26 in March.
- 2021 to 2022. Revenue jumped 69% to US$38.7 million in 2021, helped by strong chip demand in Taiwan and higher testing prices. Net profit went from US$0.4 million to US$9.4 million. In 2022 it reached US$11.2 million.
- 2023. Revenue fell 12.5%. Net profit fell 69.7% to US$3.4 million.
- 2024 to 2026. Revenue recovered to US$46.4 million in 2025, but net profit fell 24.8% to US$3.9 million. In the first half of 2026, the company put surplus cash into investment-grade bonds.
- November 2026. Tong Hsing offered S$2.30 a share in cash.
The company reports in US dollars. The table below is in Singapore dollars, converted by TradingView, so the numbers will look a bit different from the company’s own announcements (for example, the 2018 loss of US$5.0 million shows here as S$6.7 million).
| Year | Revenue (S$m) | Net profit (S$m) | Earnings per share (S$) | Free cash flow (S$m) |
|---|---|---|---|---|
| 2010 | 72.5 | 1.9 | 0.044 | 7.2 |
| 2011 | 51.6 | -7.8 | -0.191 | 21.1 |
| 2012 | 46.5 | -4.5 | -0.115 | 8.2 |
| 2013 | 45.5 | 0.9 | 0.025 | 15.6 |
| 2014 | 48.2 | 3.9 | 0.109 | 16.0 |
| 2015 | 45.4 | 5.1 | 0.143 | 14.8 |
| 2016 | 40.0 | 5.1 | 0.146 | 5.4 |
| 2017 | 38.7 | 3.5 | 0.098 | 5.3 |
| 2018 | 30.7 | -6.7 | -0.191 | 4.6 |
| 2019 | 30.5 | -4.5 | -0.128 | 3.9 |
| 2020 | 31.6 | 0.5 | 0.014 | 4.3 |
| 2021 | 52.0 | 12.6 | 0.359 | 10.6 |
| 2022 | 63.9 | 15.5 | 0.441 | 16.7 |
| 2023 | 54.5 | 4.6 | 0.131 | 6.7 |
| 2024 | 55.5 | 6.9 | 0.200 | 3.4 |
| 2025 | 60.6 | 5.1 | 0.151 | 7.4 |
Actually, if we look at it, the earnings is not so consistent in the past, and perhaps that’s back in 2015 when I was thinking through that. I wonder whether the whether you have the cash flow to actually pay that pretty significant dividends itself.
And I eventually sort of with all of these things, you sort of like be on the fence that at a certain stage, most likely something that you have quite confidence that the cash flow will be there to pay your dividends, but you’re not sure whether it will drop off or not.
Usually that is a case of mindset of actually going in like this and seeing how it actually turns out.
My own transactions
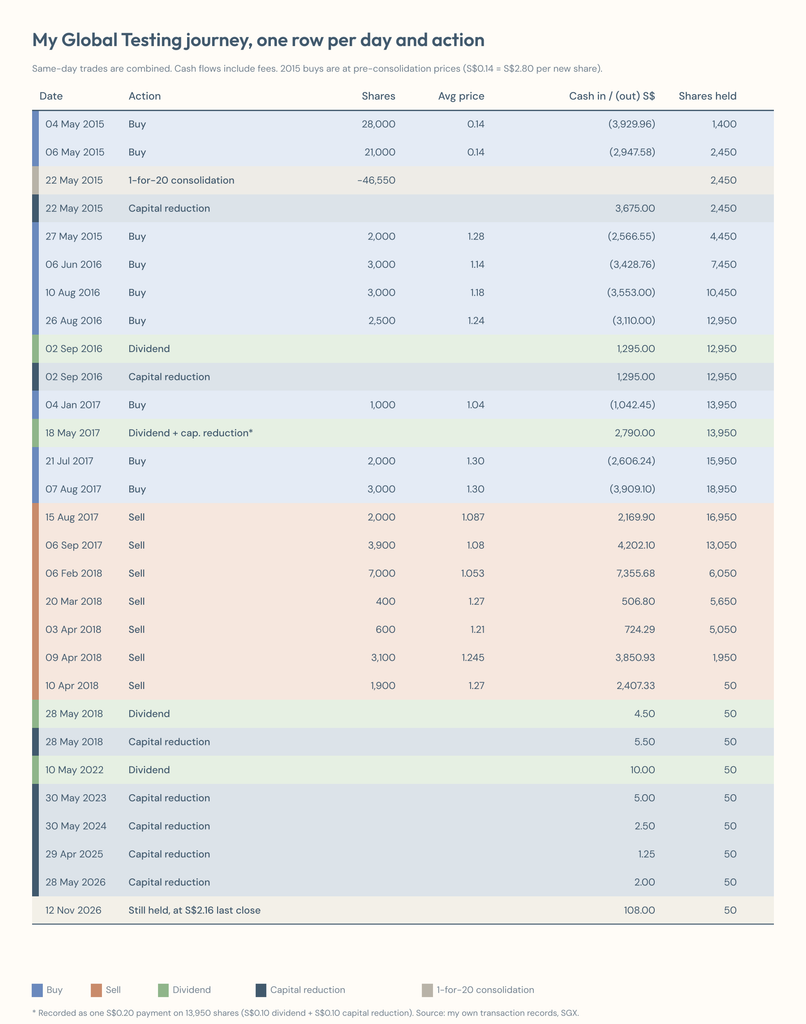
I think with Fenrir, my application to do this kind of stock portfolio tracking I can actually have better detail to actually show people like kind of my past transaction so over here you are able to see the color-coded table of my transactions:

A few things to know about my records:
- My two May 2015 buys were at S$0.14 a share, before the 1-for-20 consolidation. That’s S$2.80 per new share.
- Bought: S$27,094, including fees.
- Sold: S$21,217, after fees.
- Dividends and capital reductions: S$9,086.
- Still held: 50 shares, worth S$108 at the S$2.16 market price, or S$115 at the S$2.30 offer.
- Net gain: about S$3,300, or 1.12 times my money.
The chart below shows when the money went in and out.

I sold 18,900 shares between August 2017 and April 2018, at prices between S$1.03 and S$1.27, an average of S$1.125.
I think that’s a nice shot to see prices and when we sell it. I think maybe next time I will kind of like do this more because it’s not something that I was able to do to actually help relate when did all these transactions happen about the prices. So sometimes some of these LLMs also teach me a thing or two about what are good illustrations to show relationships
How was My Overall Return?
Returns based on Money Weighted Return (XIRR)
A money-weighted return is a fancy way of saying the return that accounts for when I put money in and when I took it out.
Imagine I put S$1,000 into a stock that doubles in the first year, then top up another S$10,000 just before it falls 20%. A plain average of the two years makes it look fine. But most of my money was invested for the bad year. The money-weighted return captures that, because it gives more weight to the years when more of my money was at work.
Here are my annualised money-weighted returns, valuing the shares I still held at the time.
| Returns to this Date | Annualised return |
|---|---|
| End of 2016 | 7.3% p.a. |
| End of 2017 | 5.6% p.a. |
| My last sale (10 April 2018) | 10.6% p.a. |
| Today, at S$2.16 | 10.6% p.a. |
| At the S$2.30 offer | 10.6% p.a. |
I left out 2015, because eight months is too short to mean anything. Today’s figure barely changes from 2018 because I only hold 50 shares. My real result was locked in when I sold.
Actually included a period where I’ve already sold off most of it, left only about 50 iShares.
So you’ll be able to see that if it’s kind of based on the last sale, the XIR is about 10.6%, which is meaning that majority of the holdings deciding actually earning 10.6%, and whatever that I am I have today, they account for significantly less than in terms of the returns
If I invested in an MSCI World Index instead
I compared my numbers with the iShares Core MSCI World ETF, which tracks developed-market shares around the world and reinvests dividends. I converted it into Singapore dollars.
- The index itself: from May 2015 to today, MSCI World returned about 10.7% p.a. in SGD.
- Same money, same dates: if I had put the same S$27,094 into MSCI World on my buy dates and left it, I’d have about S$83,500 today. That’s 3.1 times my money, or 11.3% a year.
- My actual result, reinvested: I received S$30,303 back in sales and payouts. If each dollar had gone into MSCI World the day it arrived, I’d have about S$84,650 today.
So I roughly matched the index. I did it with one small, illiquid stock instead of the whole world.
Here’s a simpler way to compare, with no timing of my own in it. Imagine S$100 put into each on 22 May 2015, with every payout reinvested.

For a single stock is a 10% return on a single stock is impressive.
This chart will let you see that actually there’s maybe an easier way of doing it. Of course, if I use the STI ETF instead of the MSCI World instead, perhaps it will be quite different.
What if I had never sold the bulk of my Global Testing shares?
At the peak I held 18,950 shares. I put in S$27,094 in total. If I had never sold, and kept every payout in cash:
| What actually happened | If I had held everything | |
|---|---|---|
| Capital invested | S$27,094 | S$27,094 |
| Capital reductions | S$4,986 | S$14,419 |
| Dividends | S$4,100 | S$8,186 |
| Sale proceeds | S$21,217 | none |
| Shares left, at S$2.30 | S$115 | S$43,585 |
| Profit | about S$3,300 | about S$39,100 |
Annualised returns can be pretty misleading if you don’t look at the actual dollar amount too. If I had kept that money compounding for another ten years, or started with a much bigger sum, the result would look very different.
In this case, you can see the profit was about $39,000. That’s probably small compared to my current portfolio, but I’d like to believe it was still a significant amount of money back then, maybe in 2015 or 2011.
The Returns if Someone buys after I sold off and held till today
I also looked at what a person would have made buying one day after my last sale (11 April 2018, at S$1.27) and holding to today.
- At S$2.16: 12.9% a year, 2.26 times the money.
- At the S$2.30 offer: 13.6% a year, 2.37 times the money.
- Payouts did a lot of the work. Price alone gives only 6.4% to 7.2% a year. The payouts added S$0.715 a share, which is 56% of that S$1.27 starting price.
Net Cash Was 93% of Market Cap Before the Offer
I think I should pay more attention to how much cash can build up on the balance sheet. In the global testing case, you can see how the cash builds up in the table below.
| 1 June | Share price (S$) | Market cap (S$m) | Net cash at prior year-end (S$m) | Net cash as % of market cap |
|---|---|---|---|---|
| 2016 | 0.95 | 33.5 | 13.1 | 39% |
| 2017 | 1.36 | 48.0 | 11.7 | 24% |
| 2018 | 1.03 | 36.4 | 9.2 | 25% |
| 2019 | 0.65 | 22.9 | 3.1 | 13% |
| 2020 | 0.26 | 9.2 | 2.3 | 25% |
| 2021 | 0.35 | 12.3 | 5.0 | 41% |
| 2022 | 1.17 | 41.2 | 14.7 | 36% |
| 2023 | 1.03 | 36.0 | 23.6 | 66% |
| 2024 | 1.02 | 35.6 | 26.2 | 74% |
| 2025 | 1.05 | 35.4 | 27.6 | 78% |
| 2026 | 1.35 | 45.0 | 31.9 | 71% |
| Just before the offer | 1.03 | 34.4 | 31.9 | 93% |

Just before the offer, the market cap was S$34 million and net cash was S$32 million. The business itself was priced at about S$2 million.
We can see why they would pay more than a 100% premium from the last traded price. Looking back, if I see a company trading at about 90% of its market cap in cash, I think I would have parked some money in it. I know it also pays a dividend, and that’s a decent return for waiting while the cash is sitting there.
The downside is that the company could turn out to be a fraud. If that happens, even after nine or ten years of holding it, I’d have nothing to say for myself.
I guess this is also a byproduct of what SGX is trying to do, which is to push most of our companies to increase shareholder value so that the exchange becomes more vibrant.
In this case, I’m not sure they actually want to enhance shareholder value. But if a company exits at a price 100% higher than the last traded price, that does enhance shareholder value in a way.
The Dividends and Capital Reductions
A capital reduction is the company handing back part of the money shareholders originally put in. A dividend is paid out of profit.
Here’s one way to picture it. A dividend is a restaurant sharing out this year’s takings. A capital reduction is the owner giving back part of the money the partners put in to open it. Either way, you get cash. The difference is where it came from.
Here’s the Capital reduction and dividends paid per share, set against the 1 June share price.
| Year | Capital reduction (S$) | Ordinary dividend (S$) | Total (S$) | 1 June price (S$) | Payout Yield % of price |
|---|---|---|---|---|---|
| 2016 | 0.10 | 0.10 | 0.20 | 0.95 | 21.1% |
| 2017 | 0.10 | 0.10 | 0.20 | 1.36 | 14.7% |
| 2018 | 0.11 | 0.09 | 0.20 | 1.03 | 19.4% |
| 2019 | 0.10 | none | 0.10 | 0.65 | 15.4% |
| 2020 | none | none | 0 | 0.26 | |
| 2021 | none | none | 0 | 0.35 | |
| 2022 | none | 0.20 | 0.20 | 1.17 | 17.1% |
| 2023 | 0.10 | none | 0.10 | 1.03 | 9.7% |
| 2024 | 0.05 | none | 0.05 | 1.02 | 4.9% |
| 2025 | 0.025 | none | 0.025 | 1.05 | 2.4% |
| 2026 | 0.04 | none | 0.04 | 1.35 | 3.0% |

In five of the seven years to 2022, shareholders were paid about 15% to 21% of the share price in cash. That’s the kind of yield that makes a stock look very juicy.
Added up since 2016, that’s S$0.625 per share from capital reductions and S$0.49 from dividends, so S$1.115 per share. And that’s on top of the 2015 payout of about S$1.50 per share.
Why the payouts shrank
Between 2016 and 2018, the company paid out more than it earned in free cash flow. Payouts were about S$7.1 million a year, against free cash flow of S$4.6 to 5.4 million. That’s why cash fell from US$9.3 million to US$5.0 million over those years.
After 2022, the payouts got much smaller (S$0.025 to S$0.10), while the cash pile kept growing. Part of the reason net cash reached S$32 million is that less was paid out.
Global Testing’s Poor Liquidity
Global Testing is very illiquid. That means few shares trade, so it can be hard to buy or sell a large amount without moving the price.
- Typical day: the median day had only about 5,000 to 14,000 shares traded, roughly S$5,000 to 18,000.
- Turnover: in a normal year only 3% to 8% of the whole company changed hands. The exceptions were 2017 (about 20%) and 2022 (about 29%).
- Quiet days: in 2020, only 84 days had a recorded trade.
In 2017 and early 2018 it was still possible to sell in size. By 2019 and 2020, turnover had dropped to 3.5% and 2.5%, and the price was S$0.26 by March 2020. Selling then would have been hard, and at a terrible price.
Tong Hsing’s S$2.30 Is a 129% Premium, or About S$45 Million for the Business
On 11 November 2026, Tong Hsing offered S$2.30 a share in cash, valuing the company at about S$76.7 million.
- The premium: about 129% above the one-month volume-weighted average price before trading was suspended. That’s the average price over the month, with more weight on days when more shares traded.
- How it works: a scheme of arrangement, a way for the buyer to take over all the shares. It would lead to delisting from the Singapore Exchange.
- What still has to happen: approval from shareholders, the Taiwanese investment authorities, the Singapore Exchange and the Singapore courts.
- The reaction: the shares rose about 110% to S$2.16 from S$1.03 on the day. They still trade below S$2.30 because the deal isn’t unconditional yet.
- The conflict: Mr Chen sits on both sides. Reports say he and the other interested directors stayed out of the board discussion and vote, and that independent advisers gave opinions on the price. I haven’t read that opinion myself.
Take the S$76.7 million offer and subtract about S$32 million of net cash. That’s roughly S$45 million for the business itself, against about S$2 million a day earlier. That’s still cheap against about S$15.6 million of EBITDA, but nowhere near the price the market was charging.

Kyith is the Owner and Sole Writer behind Investment Moats. Readers tune in to Investment Moats to learn and build stronger, firmer wealth foundations, how to have a Passive investment strategy, know more about investing in REITs and the nuts and bolts of Active Investing.
Readers also follow Kyith to learn how to plan well for Financial Security and Financial Independence.
Kyith worked as an IT operations engineer from 2004 to 2019. Currently, he works as a Senior Solutions Specialist in Fee-only Wealth Advisory Firm Providend. All opinions on Investment Moats are his own and does not represent the views of Providend.
You can view Kyith’s current portfolio here, which uses his Free Google Stock Portfolio Tracker.
His investment broker of choice is Interactive Brokers, which allows him to invest in securities from different exchanges all over the world, at very low commission rates, without custodian fees, near spot currency rates.
You can read more about Kyith here.
Premier Protein 30g High Protein Shake, Chocolate, 12 Pack | 160 Calories, 24 Vitamins & Minerals, No Added Sugar, Supports Muscle Health, Gluten-Free, 11.5 oz
$31.98 (as of November 13, 2026 03:23 GMT +00:00 - More infoProduct prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on [relevant Amazon Site(s), as applicable] at the time of purchase will apply to the purchase of this product.)
Nespresso Vertuo, Barista Flavored Pack, Medium Roast, 30-Count Coffee Pods | Medium-Roast Coffee Capsules, Caramel, roasted hazelnut and sweet vanilla flavors
$42.00 (as of November 13, 2026 03:23 GMT +00:00 - More infoProduct prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on [relevant Amazon Site(s), as applicable] at the time of purchase will apply to the purchase of this product.)
Interactive Dog Toy Ball, Automatic Bouncing for Indoor Chase Play (Blue+Orange(for Small to Medium Dogs))
$29.99 (as of November 13, 2026 03:26 GMT +00:00 - More infoProduct prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on [relevant Amazon Site(s), as applicable] at the time of purchase will apply to the purchase of this product.)
EDPACP Interactive Dog Ball Toys, Automatic Moving and Rolling Dog Toy with 3 Modes, E-TPU Wicked Balls for Medium/Large Dogs, IP54 Waterproof, Blue
$25.99 (as of November 13, 2026 03:26 GMT +00:00 - More infoProduct prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on [relevant Amazon Site(s), as applicable] at the time of purchase will apply to the purchase of this product.)

Post Comment