Unlock the Secret Strategy Smart Entrepreneurs Use to Pay Themselves a Salary with ROBS—And Why You’re Missing Out If You’re Not Doing It Yet

So, you’ve decided to kickstart a business using a Rollover for Business Startups (ROBS). That means you’re not just an investor sitting on the sidelines—you’re stepping into the ring, actively shaping the future of your own company. But here’s the million-dollar question (literally): can the business pay you a salary? Spoiler alert: yes, but there’s a catch. It’s all about a legit, well-structured setup and keeping that paycheck reasonable.
Let’s unpack this. Paying yourself with ROBS isn’t the same as taking a direct swipe from your retirement stash for personal spending. No, no, the business is essentially your employer here—your salary reflects the real work you’re doing, not just “Hey, here’s your retirement cash, enjoy!” That distinction is crucial.
Pay Yourself for the Hustle You Bring to the Table
When you fund a business through ROBS, you’re generally clocking in as a bona fide employee. Your salary should mirror what you actually do—think of it as an honest paycheck for honest work. Now, what’s “reasonable”? Glad you asked. That depends on a few things:
- The nitty-gritty: your tasks and hours logged
- What others in similar roles are making in the market
- How fat—or lean—the company’s wallet currently is
- Your own skills, background, and experience credentials
Linking your paycheck directly to the work you perform doesn’t just make sense—it’s your ammo in case anyone questions how you’re paying yourself through ROBS. Plus, it keeps everything above board.
Don’t Let Compliance Ghost You—Set Salaries the Right Way
ROBS isn’t a free-for-all cash grab; it comes with a rulebook—think retirement plan regulations and corporate governance. Treating your salary like a rogue ATM withdrawal from the company can land you in hot water. Instead, weave your compensation neatly into the company’s existing payroll rhythm. Keep those retirement-plan funds strictly for business capitalization, not personal spending sprees.
Documentation? Oh yeah, that’s your best friend here. Payroll logs, detailed job roles, and evidence supporting your pay rate help make your case airtight. And don’t go it alone—partnering with savvy ROBS 401(k) providers gives you ongoing compliance muscle so you can avoid unexpected roadblocks.
Cash Flow Real Talk: Your Salary Isn’t a Blank Check
Just because you *can* pay yourself doesn’t mean you should max out the payroll right outta the gate—this isn’t winning the lottery. Early days are tricky: bills, inventory, equipment — the business needs cash to breathe. Before you slap that salary onto the books, chew on how it impacts your operating budget.
Paying yourself too much, too soon? That’s like robbing Peter to pay Paul—your business could end up tight on essential resources, and your growth stalls. Balance is the secret sauce.
Pango Financial: Your ROBS Wingman
Rolling with ROBS to fund your dream biz means juggling your “employee” hat with the compliance tightrope. Done right, a smart salary plan not only supports your paycheck needs but keeps your company’s financial health intact. It’s all about playing the long game here.
At Pango Financial, we get the grind—we’ve helped countless entrepreneurs flip eligible retirement funds into business fuel. Plus, we handle the paperwork and admin headaches so you don’t have to lose focus on growing your empire. Curious about your best funding fit? Check out our business funding solutions tool—because your next move should be the right one.

Apple Watch Series 12 GPS 46mm Smartwatch | Black Aluminum Case, Black Sport Band - M/L. Health + Fitness + Sleep Tracking, Heart Rate, Safety
$439.99 (as of September 22, 2026 03:23 GMT +00:00 - More infoProduct prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on [relevant Amazon Site(s), as applicable] at the time of purchase will apply to the purchase of this product.)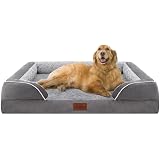
Comfort Expression Waterproof Orthopedic Dog Bed for Extra Large Dogs | Supportive Egg Crate Foam XL Pet Bed with Removable Bolster, Dog Couch with Washable Cover & Non-Slip Bottom, 42x30 Inch
$38.99 (as of September 22, 2026 03:10 GMT +00:00 - More infoProduct prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on [relevant Amazon Site(s), as applicable] at the time of purchase will apply to the purchase of this product.)
Universal Remote Control XRT140 for VIZIO Smart TV Remote Replacement XRT136 XRT260 XRT270 Smartcast D, E, M, P, V, PX Series Smart TVs
$9.98 (as of September 22, 2026 03:23 GMT +00:00 - More infoProduct prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on [relevant Amazon Site(s), as applicable] at the time of purchase will apply to the purchase of this product.)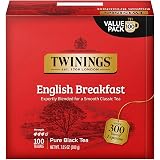
Twinings English Breakfast Black Tea Individually Wrapped Bags, 100 Count (Pack of 1), Smooth, Flavourful, and Robust, Caffeinated, Enjoy Hot or Iced, 100 Teabags
$12.38 (as of September 22, 2026 03:22 GMT +00:00 - More infoProduct prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on [relevant Amazon Site(s), as applicable] at the time of purchase will apply to the purchase of this product.)

Post Comment