
Is This the AI Revolution That Will Vaporize Personal Finance as We Know It?
Bankers rarely get a standing ovation in post-apocalyptic tales — you know, the kind where survivors huddle ‘round a campfire, burning dollar bills for warmth and reminiscing about the good old days of air travel, chicken nuggets, and simply breathing without a gas mask. Funny thing is, no one ever pauses to say, “Oh, and let’s remember the bankers. How I miss those guys!” Maybe they brought it on themselves, sure. But here’s the kicker: as Meta’s shiny new Muse AI agent rolls out, promising personal life optimization on steroids, we might soon find ourselves yearning for the familiar—and perhaps less efficient—world of traditional banking. Imagine having a tireless digital assistant, snagging the best deals and handling your money moves while you blissfully binge cat videos on the couch. Sounds like a win, right? But in this brave new world, the once mighty High Street banks, masters of riding the wave of human inertia, could be the first dominoes to fall. What does it mean when technology not only replaces tasks but threatens the entire financial ecosystem we’ve relied on? Hold onto your wallets—this AI revolution might make us reevaluate just how much we miss those bankers after all. LEARN MORE
Bankers get short thrift in post-apocalyptic storytelling. As our heroes sit around a wasteland campfire – burning dollar bills for warmth and one-upping each other with reminiscences about air travel and chicken nuggets and being able to breathe without a respirator – no-one ever says:
“Oh, and let’s remember the bankers. How I miss those guys!”
I mean, perhaps the bankers brought it on themselves?
Either way, we might soon discover how much we miss banks as we know them, if the latest AI-will-eat-your-hamster scare stories come true.
That’s because ever since the launch of Meta’s Muse AI agent a few weeks ago, people have been fretting about what will happen if when everyone has their own personal life-optimiser.
Picture a 24/7 digital slave working tirelessly to get you the best deals for your money, and freeing up more time for you to loaf on the sofa scrolling through cat videos.
It’ll be like having your own Robo Martin Lewis! Only instead of “dead or alive you’re coming with me” it’ll be more “pay me 5% interest or boost my air miles, otherwise I’m out the door.”
In such a war on the status quo, the High Street banks – big beneficiaries of what my co-blogger The Accumulator has generously called the superpower of human inertia – would be among the first to fall.
Agent on it
Remember: you and I are exceptional. We read personal finance blogs, watch our pennies, nurture our savings, and invest in low-cost index funds for the long-term.
But there are many other people out there who move through their financial lives with all the efficiency of a sloth jogging through treacle.
I’m not even talking about those who treat a 26.5% credit card charge for last month’s spending spree as a cost of business – let alone those with no money at all.
No, I mean the could’ve-been millionaires next door. The ones who don’t save or invest wisely, are tardy about remortgaging, and never make their spare change work harder for them.
For instance, a recent estimate found there’s £327bn sitting unproductively in bank accounts that pay less than 1.5% interest on savings.
Seriously?
2019 called and it wants its near-zero rate environment back.
24/7 banking
To be fair, I imagine most of those billions are made up of a few quid here and there. There can’t be many five-figure cash piles sitting around in a typical current account earning next to nothing, can there? (Or am I just hopelessly naive?)
I mean, even I’ve left a few hundred quid in a half-forgotten account for a time. We all lead busy lives. Those cat videos won’t watch themselves.
But what if you didn’t have to keep on top of any of this stuff anyway, because your personal AI agent could move your money for you?
All you’d do is mutter a suitable prompt –“Hey AI Marty, round up all my loose cash from my old bank accounts and stick it somewhere lucrative, but not at Betfair like you did last month because we’ve talked about that” – and now you’re making hay.
Meanwhile your legacy bank is making, well, nada.
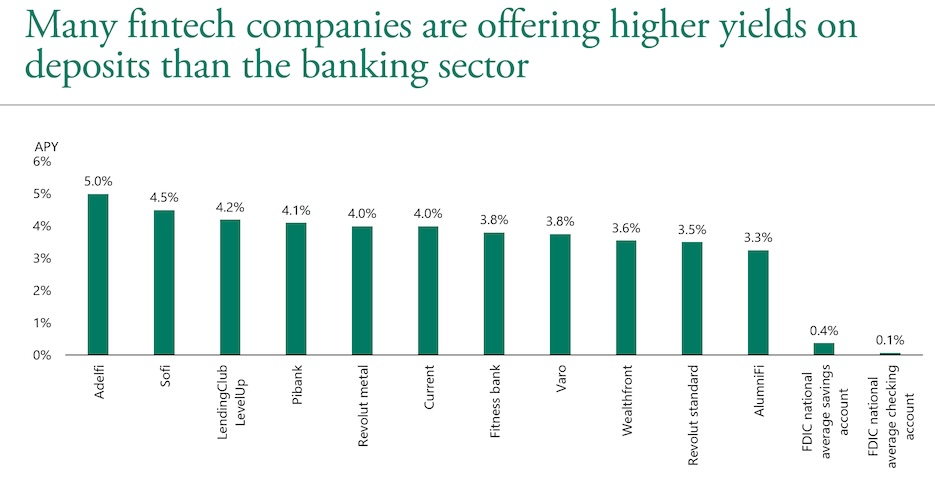
You don’t need a super-intelligence to see that your money is better served in the challenger accounts to the left in the graphic below than the status quo offerings on the right:

Source: Apollo
True, moving a few quid out of a near-dormant account you only opened for a three-month 2% bonus five years ago won’t have JP Morgan’s Jamie Dimon quaking in his loafers.
But £300 here and £300 there across the entire population?
Soon you’re talking real money.
Block and tackle
The Financial Times ran the numbers for the US banks and – I hope you’re sitting down Jamie – it found that making all that idle cash work harder could cost the banking sector $500bn.
Yes, that’s billion with a ‘b’ for “Bugger!”
If you’re a banker.
To be clear, that’s not $500bn in lost income. Rather, it’s the hit to bank valuations should the $20 trillion in US bank accounts always goes to where it’s treated better, and hence profits fall.
But it’s likely a high estimate, because the banks won’t go down without a fight.
Who knows, perhaps they will respond with truly wonderful higher-value products that rightly earn their spread by giving excellent value to us customers?
Or maybe they’ll just block AI agents from accessing their bank accounts.
You won’t be surprised to learn which approach the banks have gone for first.
Although to be fair, if I ran a bank I’d want to keep any autonomous agent created by Mark Zuckerberg at arm’s length, too.
At least until it had learned its lessons first with someone else’s money.
Agents everywhere
Banning agents won’t be a long-term solution though, if agents really do proliferate. It’d be like banning phone calls, and insisting customers bring their passbooks to their local branch to withdraw their money.
In fact this parallel can go further, to the online and app-only bank accounts that for years have offered higher rates than on the High Street, leaving offline customers missing out.
Similarly, if powerful and trustworthy AI agents do work and spread as promised, then you’ll need to use them just to keep up with the Jones’ savings.
Abstaining won’t be costless.
Forget-me-not finance
Indeed it’s all a bit daunting if you play forward the consequences of agents everywhere.
Obviously nobody around these parts will complain if AI makes it effortless to get the highest interest rate on cash. Nor if personal finance agents invest someone’s monthly savings into a diversified passive portfolio faster than they can say: “I wonder if it’s time to buy Bitcoin?”
And on a related note, shares of media firms like The New York Times and Spotify fell after the Muse launch, on the grounds that in the agent era, nobody will pay for subscriptions they’ve forgotten about. (Something that never happens with Monevator membership, I hope…)
Gyms could suffer too if customers are reminded by their AI agent in March that they’re still paying for the good intentions of January – even though the only deadlift they’ve done since February was hoiking two party-sized boxes of Krispy Kremes onto the kitchen counter.
An AI agent won’t forget. What’s more it’ll go through all your bills, without getting bored or flagging, to keep checking you’re still into all your standing orders staying that way.
Know what you’re not doing
On the face of it then, promising stuff.
Though perhaps it could spell doom for personal finance and investing outlets like Monevator?
Already we are being choked off by AI-powered excerpts in Google that mean people don’t need to visit our actual articles so often for answers.
I must admit that the possibility of AI ‘making it irrelevant for anyone to know how to manage their money because an agent does it all for them’ isn’t something that came up during my SWOT strategy sessions.
But actually, I don’t quite believe this is an extinction-level threat for us.
Consider driving as an analogy. It’s one thing not to understand how a car works. But you still need to know where you want to go to use a car properly.
Similarly, AI agents could well remove much of the legwork from managing money.
But that will leave more time for us all to think about our big picture financial independence planning and other higher-order matters.
Well, hopefully.
Costs and consequences
I also have some doubts about how far this agent revolution can run.
For one thing, there’s the privacy aspect.
I do appreciate that half the population is already living in their own opt-in Truman Show every day online.
But there’s a difference between carefully curating a social media image for the world, and letting a Californian oligarch gate-keep every penny that passes through your bank account.
We can also expect companies to fight back against any AI-enabled consumer empowerment.
Banning agents is only the crude first response. It will soon give way to packaging services in such a way that it’s even harder to unpick where you’re profiting and where a company benefits.
That’s a wrap
Consider an all-in package like Amazon Prime, for example.
By bundling together free shipping, video streaming, advertising, discounted movie tickets, and more, Prime turns pricing its services into more of a ‘vibe check’.
Your AI agent might tell you such a bundle is not worth the money. But faced with the right warm and fuzzy overall proposition, you might not believe it – or even care.
Less nefariously, the US wholesale grocer Costco has millions of fans who pay annually for the right to shop in its stores.
Costco members never tire of telling you about the bargains they get. Yet Costco has somehow still grown into a $445bn behemoth, so it’s making money somewhere.
And then there are those ever-looming existential issues.
True, the agent version of AI Armageddon doesn’t unleash backyard bioweapons upon us, let alone a Terminator.
But AI agents with the best of intentions could still be plenty disruptive.
Paging Adam Smith
What happens, say, when tens of billions of AI agents are all running around chasing the same products at the lowest prices, at the same time?
Capitalism breaks, perhaps?
An article in The Atlantic quotes the Wharton School professor Rory Van Loo:
“If, all of a sudden, people could purchase whatever they wanted at the lowest price with the perfect ability to see every possible option, there’d be a lot of volatility in the world. It would seem highly efficient from an economic standpoint, but it could have devastating effects.”
Picture one million personal agents all switching their consumers to a new brand of paper towels on Amazon because a markdown made them three cents cheaper.
The same Sweetgreen salad is $18 one week and $38 the next. Your electric bill is $150 one month and $450 the month after, and you’re uncertain with each payment whether your local utility is about to go bankrupt.
“Stocks are bought and sold fast; markets change and plummet – such that we have a stop button for it, because it can go off the rails,” Van Loo noted. “But we don’t have those kinds of protections in most other markets.”
I imagine straight sticker prices could eventually converge – because any retailer deviating from the current market norm would get no customers. The agents would just go elsewhere.
In such a world, the same model of toaster selling for different prices in different shops might seem as odd as if £10 in London was worth £20 in Glasgow.
This might sound utopian. But as The Atlantic points out, collateral damage could show up all over the place.
Including – to return to where we started – in banking.
Credit Crisis 2.0
Anyone over 40 who is reading this website will remember the queues outside Northern Rock during the Great Financial Crisis.
Customers of Northern Rock feared it might not be able to give them their savings back if the situation got worse. So they decided to jump the gun and take their money out, pronto:

The next bank run might not wear a comfy cardigan
This is essentially how all bank runs work. But at least in the old days you had to schlep down to the local branch with a bank statement to wave around – or to keep hitting refresh on a web browser to log into an overburdened home page – to do your bit to make the situation worse.
But AI agents can do this stuff in the blink of an eye. As a result, billions – trillions – could slosh from one bank to another, driven by whatever factor the agents deem most important.
Sure, that should be to secure better interest rates in the calm times.
But perhaps the agents too would be moved by rumours and miscommunications during the next global credit crisis, just like everyday humans but on industrial strength steroids. Banks could go bust on the back of a well-timed tweet.
Could that be prevented? Of course – banks could insist on minimum time lock-ups to gate much more of our money.
But this undoes the promise of that frictionless AI revolution. And if some banks opt out, then they might quickly amass the money of the others. The incentives are mind-bending.
You can see how it could all spiral in very unpredictable ways – and fast.
Buy now, pay later
Nearly four years on from the launch of ChatGPT, it seems to me that AI is following the template set by other revolutionary technologies and the futurist Roy Amara’s famous dictum:
We tend to overestimate the effect of a technology in the short run and underestimate the effect in the long run.
Maybe agents will never be reliable enough for true mass adoption. Tech-savvy nerds enjoy figuring out why their automated shopping assistant ordered five tons of horse manure to be dumped on their front lawn. Normal people just want things to work.
But if agents do eventually get inserted into all our transactions – and civilisation is brought to its knees because we cut human bankers out of the loop – then consider yourself warned.
Saving the bankers won’t draw many recruits to a Butlerian Jihad anytime soon.
Besides, before we can have a backlash against the AIs, we must fully lash ourselves to their masts.
But it does make you wonder if getting a higher interest rate while you sleep will ultimately prove to be worth it.
Apple iPad 11-inch: A16 chip, 11-inch Model, Liquid Retina Display, 128GB, Wi-Fi 6, 12MP Front/12MP Back Camera, Touch ID, All-Day Battery Life — Blue
$399.00 (as of October 27, 2026 03:23 GMT +00:00 - More infoProduct prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on [relevant Amazon Site(s), as applicable] at the time of purchase will apply to the purchase of this product.)
CELSIUS Assorted Flavors Official Variety Pack, Functional Essential Energy Drinks, 12 Fl Oz (Pack of 12)
$22.49 (as of October 27, 2026 03:13 GMT +00:00 - More infoProduct prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on [relevant Amazon Site(s), as applicable] at the time of purchase will apply to the purchase of this product.)
Bloom Nutrition Zero Sugar Energy Drink, Apple Crisp, 12oz 12pk | 180mg natural caffeine with prebiotics, green tea extract & lychee for energy, focus and feel-good refreshment.
$24.99 (as of October 27, 2026 03:13 GMT +00:00 - More infoProduct prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on [relevant Amazon Site(s), as applicable] at the time of purchase will apply to the purchase of this product.)
Coca-Cola Zero Sugar Soda Soft Drink Fridge Pack Cans, 12 fl oz, 12 Pack | Carbonated cola soda pop with zero calories
$7.68 (as of October 27, 2026 03:13 GMT +00:00 - More infoProduct prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on [relevant Amazon Site(s), as applicable] at the time of purchase will apply to the purchase of this product.)

Post Comment