
SEC’s Bold Two-Track Strategy on Private Assets: What It Means for Your Next Big Investment Move
Imagine cracking open the private market doors for just $100 and a couple of hours answering some multiple-choice questions — suddenly, the exclusive club with that million-dollar net worth entry fee might feel a little less intimidating. That’s exactly the SEC’s big idea with the new FINRA-developed accredited investor exam they’re mulling over. Anyone 18 or older could take this roughly 75-question test, and if you pass, bam, you’re accredited for a decade. Sounds like the great equalizer in private investments, right? But—here’s the kicker—while the SEC is busy expanding who gets to play in this high-stakes sandbox, they’re also zooming in on the nitty-gritty of how these private assets get priced. Because, let’s be real, if the numbers behind the scenes aren’t crystal clear, new investors could end up paying way more than what’s fair. It’s like Spider-Man’s wisdom mashed up with Walt Whitman’s multitudes — with great access, comes great responsibility to get valuations just right. Ready to dive into the twists and turns of this evolving landscape? LEARN MORE
For about $100 and two hours of multiple-choice questions, the average Joe could soon qualify to buy into private offerings. That is the premise of a FINRA-developed accredited investor exam the SEC is now considering. Anybody 18 or older could sit for roughly 75 questions, and a passing score would qualify an investor for accredited status for 10 years.
The exam is part of a package the Commission released on September 30 to promote the “responsible retailization” of private markets, currently reserved for those with a net worth north of $1 million or an income above $200,000 ($300,000 jointly). Proposed rules would let advisers charge performance fees to any accredited investor and to registered funds such as BDCs, a change the SEC expects will cause private-markets managers to offer more products designed for individuals. Another proposal would loosen repurchase scheduling for interval funds, one of the main ways non-accredited investors already reach private credit.
Even as it widens access, however, the SEC is taking a microscope to how these assets are valued. Two days before the proposals, the Office of the Chief Accountant and the Division of Investment Management published a staff statement on fair value for private assets. Private credit in registered fund portfolios grew from $170 billion at the end of 2020 to $270 billion at the end of 2025. Those loans rarely trade, so their value usually rests on Level 3 inputs—accounting shorthand for lots of assumptions and a good deal of judgment.
The statement asks funds and advisors to value private credit the way a market participant would, factoring in prevailing credit spreads and liquidity. It also warns against boilerplate disclosure and singles out payment-in-kind (PIK) interest, which lets a borrower cover interest by adding it to the loan balance instead of paying cash. The fund still books that as income, so a PIK-heavy portfolio can look healthier on paper than it does in cash.
For individual investors, this comes down to price. Interval funds and non-traded BDCs set their share prices from these valuations. If valuations run high, new investors could pay more than the assets’ underlying value would support. More than half of interval fund assets were classified as Level 3 at the end of 2025, according to figures cited by Simpson Thacher. If the performance-fee proposal is adopted, valuation practices could take on additional significance because those valuations may also affect adviser compensation.
Read side by side, the two releases could appear to send mixed signals about the SEC’s approach to private assets. One official had a hand in both: Investment Management Director Brian Daly co-signed the valuation statement and called performance fees “a defining characteristic of private funds.” Walt Whitman made a career out of “containing multitudes.” Daly might say the more relevant line comes from Spider-Man: “With great power comes great responsibility.”
In fact, the SEC’s two positions may be more complementary than contradictory. As access to private assets expands, the importance of rigorous valuation, transparent disclosure and appropriate controls grows with it. For funds and advisers, that means greater attention to how Level 3 assets are valued and documented, particularly when those valuations affect investor returns or adviser compensation. For investors, broader access may create new opportunities, but it also makes understanding how a fund arrives at its reported value increasingly important.
—
Don’t just read about the trends. Leverage them. Explore Intelligize with a free trial.
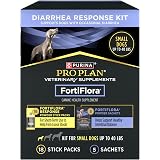
Purina Pro Plan Veterinary Supplements Diarrhea Response for Dogs | Diarrhea Response Kit for small breed dogs, 2-stage support, features FortiFlora Response and FortiFlora
$34.99 (as of October 7, 2026 03:20 GMT +00:00 - More infoProduct prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on [relevant Amazon Site(s), as applicable] at the time of purchase will apply to the purchase of this product.)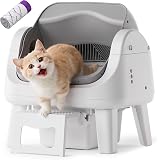
Automatic Litter Box, Self Cleaning Litter Box with Safety Sensors | Three layers of protection—infrared sensing, front-step response, and a half-gear limit—support safer automatic cleaning.
$99.99 (as of October 7, 2026 03:20 GMT +00:00 - More infoProduct prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on [relevant Amazon Site(s), as applicable] at the time of purchase will apply to the purchase of this product.)
GNMN Active Noise Cancelling Ear Buds Wireless Earbuds 96hrs Playback Bluetooth Headphones Dual Battery Display Stereo Bass Earphones with Earhooks Microphone IPX7 Waterproof for Sports/Runing/Workout
$75.98 (as of October 7, 2026 03:27 GMT +00:00 - More infoProduct prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on [relevant Amazon Site(s), as applicable] at the time of purchase will apply to the purchase of this product.)
Apple AirPods Pro 3 Wireless Earbuds with Active Noise Cancellation | Live Translation, Heart Rate Sensing, Hearing Aid Feature, Bluetooth Headphones, Spatial Audio, USB-C Charging
$179.00 (as of October 7, 2026 03:20 GMT +00:00 - More infoProduct prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on [relevant Amazon Site(s), as applicable] at the time of purchase will apply to the purchase of this product.)

Post Comment