
SEC’s Proxy Voting Overhaul: The Silent Game-Changer Wall Street Doesn’t Want You to See!
Ever wonder what happens when corporate shareholder voting gets tossed into the fast lane of automation? Last year, Goldman Sachs faced a shareholder revolt—the largest yet—over $80 million in bonuses for its top brass, with nearly a quarter of shares simply skipping the vote altogether. Sound familiar? Well, Goldman’s now hitting the accelerator with a retail voting program designed to bring those missing ballots back on track. Thanks to a recent SEC green light for Tesla’s similar “self-driving” voting scheme, this could become the new norm across public companies. Imagine your vote on executive pay or shareholder proposals being cast automatically—unless you decide otherwise—like a Tesla on autopilot, steering through corporate governance. It’s a mix of convenience and control, but with big questions about how much influence individual investors really keep once they hand the wheel to management’s recommendations. Ready or not, the era of self-driving proxy voting is here, and it’s reshaping the corporate landscape in ways we’re only beginning to grasp. LEARN MORE
Last year, Goldman Sachs shareholders representing roughly a third of votes cast objected to $80 million in retention bonuses for CEO David Solomon and President John Waldron, the most pushback on compensation the bank has ever seen. Holders of about a quarter of its shares skipped the vote entirely. Goldman now has a plan for those missing ballots, and thanks to a letter the SEC staff sent Tesla last month, so can every other public company.
The plan is a retail voting program. Individual shareholders who enroll give standing instructions to vote their shares in line with board recommendations at every meeting. (In Goldman’s version, shareholders who sign up can still change their vote on a particular proposal or opt out of the program.) On Sept. 29, the Division of Corporation Finance issued a no-action letter to Tesla for the carmaker’s take on what it calls “issuer voluntary retail voting programs” (or IVRVPs; rolls right off the tongue). Division official Tiffany Posil wrote that the SEC’s blessing for Tesla applies to any issuer that runs a program the same way. Goldman received its own letter the day before.
Both letters build on the staff’s September 2025 letter to Exxon Mobil, the first of its kind. The appeal for these and other issuers comes down to turnout. Retail investors cast ballots at a rate of about 30%, compared with roughly 77% for institutions. When individuals do vote, they tend to side with management, but each one owns such a tiny slice of the company that many stay home out of “rational apathy.” For companies with a sizable retail shareholder base, increasing participation among investors who voluntarily elect to follow board recommendations could influence voting outcomes on matters such as executive compensation and shareholder proposals.
Retail investors hold roughly 30% of Goldman’s shares, Bloomberg reported. Goldman also plans to pitch the program to current employees and former partners, who together hold more than 7.6% of its stock. Tesla’s framework goes further on mechanics. Shareholders can enroll at any time instead of only around a specific meeting. Also, always thinking ahead on technology, Tesla envisions shareholder communication “hubs” where investors could sign up for several companies’ programs at once.
Shareholder activists see the programs as further diminution of their influence. Gadfly investor James McRitchie argued that a better design would let investors set standing instructions around their own priorities, such as climate protection or executive pay limits. He called the approved version “blatantly one-sided.” Supporters of these programs emphasize their potential to increase retail shareholder participation, while critics question whether defaulting to management recommendations provides investors with sufficient flexibility to express their individual preferences.
The SEC staff addressed that idea in new interpretive guidance issued Oct. 8. Companies do not have to run retail voting programs at all, the staff said, and those that do need not offer alternative standing instructions like voting against board recommendations. With certain caveats, the guidance also clarified that a program could let shareholders follow a third party’s voting recommendations.
Retail voting programs saw little use during the 2026 proxy season. But with Tesla’s framework allowing enrollment between meetings, companies interested in implementing a program for 2027 can start preparing now. “Full self-driving mode” is here for issuers that want it.
For issuers, the opportunity is clear: greater retail participation could change voting dynamics on executive compensation, shareholder proposals and other governance matters. The challenge will be balancing that opportunity with transparency, shareholder choice and investor expectations. Self-driving proxy voting may be here, but companies still need to keep their hands on the wheel.
—
Don’t just read about the trends. Leverage them. Explore Intelligize with a free trial.
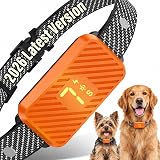
Smart Bark Collar for Large Medium Small Dogs, Rechargeable No-Bark Collar, Stop Barking Collar, 2026 Upgraded Dog Bark Collar with 3 Modes, 7 Sensitivity, Neon Orange
$25.99 (as of October 14, 2026 03:21 GMT +00:00 - More infoProduct prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on [relevant Amazon Site(s), as applicable] at the time of purchase will apply to the purchase of this product.)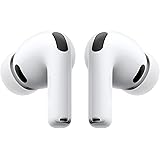
Apple AirPods Pro 3 Wireless Earbuds with Active Noise Cancellation | Live Translation, Heart Rate Sensing, Hearing Aid Feature, Bluetooth Headphones, Spatial Audio, USB-C Charging
$199.00 (as of October 14, 2026 03:21 GMT +00:00 - More infoProduct prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on [relevant Amazon Site(s), as applicable] at the time of purchase will apply to the purchase of this product.)
SHOKZ OpenDots 2 Open-Ear Clip-On Earbuds, Black, Dolby Audio, 3 Mics | Rich bass with Dolby Audio; 3-mic clear calls; 40H listening; IP57; Bluetooth 6.1; Travel/City walk/Commuting/Yoga/Pilates
$199.95 (as of October 14, 2026 03:32 GMT +00:00 - More infoProduct prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on [relevant Amazon Site(s), as applicable] at the time of purchase will apply to the purchase of this product.)
Ljusmicker for AirPods Pro 3 Case 2025 with Cleaner Kit,Black | Soft Silicone Protective Cover for Apple AirPod Pro 3rd Generation Case with Keychain for Women Men,Shockproof
$5.99 (as of October 14, 2026 03:21 GMT +00:00 - More infoProduct prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on [relevant Amazon Site(s), as applicable] at the time of purchase will apply to the purchase of this product.)

Post Comment