
Unlock the Secret Battle: Why Glenn Gaughran Says Choosing Between PRSA and Master Trust Could Make or Break Your Financial Future!
So, you’re an employer stepping into the pension world for the very first time—and already feeling like you’ve stepped into a maze without a map? Join the club! The choice between setting up a company pension scheme via a master trust or a PRSA isn’t just a tick-the-box decision. It’s about figuring out what really serves your business and your team’s financial future best. Master trusts, championed under the EU’s IORP II Directive, have surged in popularity, offering a straightforward, collective approach. Meanwhile, PRSAs bring a world of flexibility—especially when it comes to investments, even dipping toes into property ventures if you choose the non-standard route. But wait—there’s a twist. New rules might reshape the playing field soon, potentially clipping the wings of certain investment options within PRSAs. It’s enough to make even the savviest entrepreneur scratch their head. Before locking in your choice, taking stock of costs, retirement plans, and employee needs, and seeking solid, impartial advice can make all the difference between a pension plan that’s a burden and one that’s a business’s best asset. Curious to dive deeper into which path suits your company’s ambition? LEARN MORE

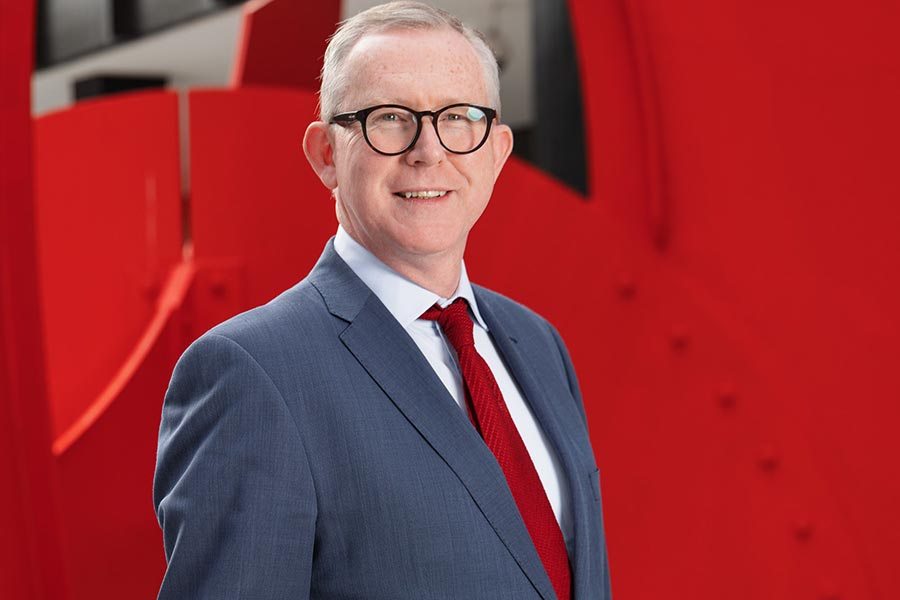
Glenn Gaughran, head of business development with the Independent Trustee Company, explains some of the pros and cons of both systems for employers
I’m a new employer who is setting up access to a company pension scheme for the first time.
Am I better to do so via a master trust or PRSA, what are the pros and cons of each and would either of these allow employees to invest in property through their pensions if they so wished?
A master trust is essentially a large group pension scheme which is set up under trust and which allows multiple employers and other individual members to all co-exist under the one trust deed. Master trusts have become very popular among employers since new EU pension governance rules (part of the EU’s IORP II Directive) came into force in 2021.
A Personal Retirement Savings Account (PRSA) is a type of personal pension plan which individuals and business owners can set up themselves.
Employer contributions can be made to both master trusts and PRSAs but each scheme has its own rules and limits in this regard which you and your employees, would need to be aware of.
There are significant differences between master trusts and PRSAs.
For employers seeking a tailored pension structure, a master trust may be the more straightforward option.
PRSAs on the other hand offer more flexibility, particularly when it comes to investments.
You are likely to have more options with investments within a PRSA than a master trust, as long as you opt for a non-standard PRSA.
With a standard PRSA, you are only allowed to invest in pooled funds such as unit trusts and life company unit funds whereas non-standard PRSAs don’t restrict your investments to pooled funds, so you have more flexibility around investments.
As master trusts are governed by the IORP II directive, a master trust pension must predominantly invest in regulated markets and be fully diversified. Direct property investment is usually not possible within master trusts.
By contrast, property can currently be purchased through a non-standard PRSA, and if required, one can even borrow within a PRSA to purchase property.
There are a number of tax advantages to purchasing property through a pension scheme but it is very important that any employees considering doing so get impartial advice first, and that they also ensure to adhere to the Revenue rules so that they qualify for the tax advantages.
It’s important to note too that new rules could be introduced which could limit the kind of assets which PRSA holders could invest their pension savings in in the future, with property being one of the assets that these restrictions could apply to.
This is as a result of proposals being developed by the Pensions Authority on the investment rules around PRSAs.
Time will tell exactly what form the new rules could take but if the Pensions Authority restricts the investment of PRSA funds to regulated markets and funds, it is possible that it would no longer be possible to invest more than 50 per cent in assets such as property, infrastructure, renewable energy and venture capital.
Borrowing for property through a non-standard PRSA might also no longer be possible on foot of the new rules.
Before deciding between a master trust and PRSA, it is important to assess which pension scheme offers the best value and is most appropriate for your employees.
Be sure too to seek impartial advice so you understand how the schemes differ and how they compare on costs.
The likes of these costs, when employees plan to retire, what they want to invest in, and what is in the best interests of pension members will help you decide which pension product will suit your company and employees best.
Bee Frontier (all-new), Wearable Personal AI that grows with you, confidential by design, transforms conversations into actionable summaries, 7-day battery, IP67 Rated, Onyx
$74.99 (as of October 17, 2026 03:33 GMT +00:00 - More infoProduct prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on [relevant Amazon Site(s), as applicable] at the time of purchase will apply to the purchase of this product.)
Minties Mint Dental Bone Treats, Tiny/Small Breeds, 80 Count | Vet-recommended mint dental bone; scrubs teeth as dogs chew; fights plaque, tartar & bad breath; no soy/wheat/corn
$22.81 (as of October 17, 2026 03:21 GMT +00:00 - More infoProduct prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on [relevant Amazon Site(s), as applicable] at the time of purchase will apply to the purchase of this product.)
Temptations Classic Crunchy and Soft Cat Treats, Tasty Chicken, 30 oz | Under 2 calories per treat, crunchy outside & soft inside, resealable tub, 100% complete & balanced, snack, meal or topper
$14.94 (as of October 17, 2026 03:12 GMT +00:00 - More infoProduct prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on [relevant Amazon Site(s), as applicable] at the time of purchase will apply to the purchase of this product.)
Amazon Fire TV Stick 4K Plus with AI-powered Fire TV Search, Wi-Fi 6, stream hundreds of thousands of movies and shows, free & live TV, find shows faster with Alexa+
$69.99 (as of October 17, 2026 03:21 GMT +00:00 - More infoProduct prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on [relevant Amazon Site(s), as applicable] at the time of purchase will apply to the purchase of this product.)

Post Comment