
Why Adding a Simple Payment Option Almost Destroyed Our Business—and What We Learned About Scaling Smarter
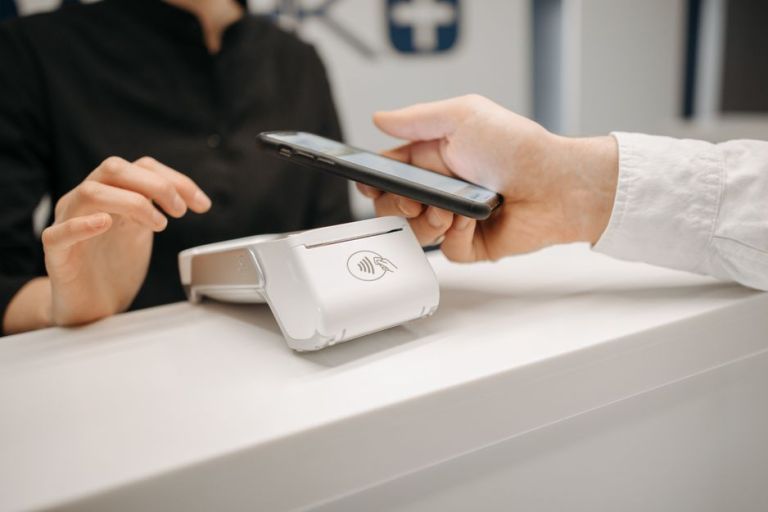
Ever been asked, “Hey, do you take that newfangled digital coin thingy?” and thought, “How hard can it be to add another payment option?” Well, buckle up, because beneath that simple yes-or-no lies a maze of unseen work, red tape, and a dash of chaos most small business owners dread. It’s like agreeing to a quick coffee meet-up and suddenly finding yourself hosting a full-blown gala. You check the fees, nod to the setup, and then… the real juggling act begins. Matching payments to invoices, untangling conversions, juggling refunds — and if all that depends on your memory, you’re in for a rollercoaster of headaches. For those venturing into the realm of digital-asset payments, the secret sauce isn’t just the transaction itself; it’s mastering the entire process behind the scenes without losing your sanity or your weekend. Ready to dive into what really goes on after the “quick setup”? Let’s unpack the hidden grind and find out whether embracing that shiny new payment method will light up your business — or just weigh it down. LEARN MORE

Key Takeaways
- Small businesses should assess actual customer demand and the full administrative workload before introducing digital-asset payment options.
- Payment receipt, asset conversion, and supplier settlement are separate activities that require clear documentation and verification.
- Consistent transaction records help businesses reconcile payments, support bookkeeping, investigate discrepancies, and manage refunds.
- Delegating payment responsibilities requires defined approval processes, controlled access, secure credential storage, and backup personnel.
- A limited pilot allows business owners to measure completed sales, staff time, processing costs, and operational risks before deciding whether to continue.
A customer asks whether your business accepts a different payment method. The request sounds simple, especially when a service provider promises a quick setup. You check the processing fee, confirm that the payment can reach you, and agree to try it.
The less visible work begins afterward. Someone needs to match the payment to an invoice, account for any conversion, explain a delay, and decide how a refund would work. If those tasks depend on the founder remembering every detail, a convenient arrangement can become a recurring administrative burden.
For small businesses considering digital-asset transactions, the useful starting point is the complete workflow. The question is whether the business can receive, document, and resolve those transactions reliably with the people and resources it already has.

Measure the Work Behind the Request
Before introducing another payment route, establish how often customers actually need it. A single inquiry may justify a conversation, but it provides limited evidence for changing the way the business operates.
Record requests over a defined period. Note the customer’s location, the type of purchase, and whether an existing payment method would meet their needs. This helps distinguish a genuine barrier to sales from a preference that rarely affects buying decisions.
Then map the additional work involved. Include initial setup, payment verification, recordkeeping, customer support, and any conversion needed before the funds can serve their intended purpose. Assign an estimated amount of staff time to each stage.
Consider a small agency whose clients occasionally request an alternative payment arrangement. If each transaction requires the owner to investigate a new process, the cost extends beyond the quoted service fee. It includes time taken away from client work and the possibility of delayed reconciliation.
A limited pilot can make that workload visible. Define which transactions qualify, who handles them, and when the pilot will be reviewed. Keep the scope narrow enough that an unexpected problem remains manageable.
Agree on the evidence that would justify continuing. That might be completed orders that would otherwise have been lost, fewer payment-related delays, or a process that staff can handle without repeated intervention.
Follow the Money Through Every Handoff
Receiving an asset, converting it, and paying a supplier are separate activities. Each has its own purpose, reference details, and completion point. Treating them as one event makes it harder to investigate discrepancies later.
Start with the commercial record. Identify the invoice or agreement, the amount owed, and the accepted payment terms. Establish who confirms receipt and what information that person needs before marking the invoice as settled.
If a conversion is necessary, document the reason separately. The business should know what it intends to receive, where the result should go, and who has authorized the operation. An employee should not have to infer these details from an informal message.
During an approved ltc to xmr conversion, the Litecoin sent and the Monero received need to remain connected in the internal record. Preserve the service reference, relevant timestamps, actual quantities, and the instruction that explains the transaction’s purpose.
That connection matters when another person reviews the activity. A wallet movement may show that assets left an address, but the business still needs evidence of the intended outcome.
Assign one person responsibility for following the operation through to completion. If responsibility changes midway, make the handoff explicit. Record what has already happened, what remains unresolved, and where the next person can find supporting information.
Also agree on an exception process. An unclear status should trigger investigation of the existing transaction before anyone starts a replacement.
Build Records That the Bookkeeper Can Use
Operational success and accounting readiness are different milestones. A transaction can be complete while its supporting paperwork remains scattered across emails, screenshots, and individual accounts.
The U.S. Small Business Administration’s business management guidance emphasizes proper bookkeeping and tracking revenue and expenses. Any additional payment method needs to fit into that established financial picture.
Before the pilot begins, ask the person responsible for the accounts what information they need. Agree on the required valuation records, fee details, references, and supporting documents for the business’s circumstances. This avoids collecting a large volume of material that still leaves essential questions unanswered.
Use a consistent record for each transaction. It should identify the commercial purpose, the person who approved it, the relevant amounts, and the location of supporting evidence. Keep sensitive credentials outside this record.
Schedule reconciliation while the activity is still fresh. Compare completed transactions with the internal log and investigate missing information promptly. Waiting until the end of a reporting period makes small discrepancies harder to explain.
Refunds deserve preparation too. Establish the process before accepting the first payment, including who can authorize a refund and how its terms will be communicated. Staff need a consistent approach when a customer asks to reverse a purchase.
A useful check is to ask an authorized colleague to explain a completed transaction from the records alone. If they need the founder’s memory to finish the explanation, the process is not yet ready for wider use.
Delegate the Process Without Sharing Everything
Small teams often confuse access with responsibility. Giving someone the ability to view a transaction does not necessarily mean they should be able to initiate another one.
Separate the tasks wherever practical. One person may prepare the details, another may approve them, and the bookkeeper may only need records of completed activity. Define these roles according to the team’s size and the consequences of an error.
For supported accounts, enable multi-factor authentication. The NIST guidance on multi-factor authentication explains how additional authentication factors strengthen protection beyond a password. Wallet keys and recovery material require their own controlled storage arrangements; they should never sit in an ordinary shared transaction spreadsheet.
Prepare a backup person for routine monitoring and escalation. They should know where instructions are stored, how to identify unfinished work, and whom to contact. A walkthrough can reveal missing steps before the main operator becomes unavailable.
At the pilot review, compare the benefit with the full workload. Include staff time, unresolved exceptions, and reconciliation effort alongside fees and completed sales. Continuing, narrowing, or ending the arrangement should all remain possible outcomes.
A payment option becomes useful when the business can support it beyond the initial transaction. Clear responsibilities and complete records make that judgment easier. They also allow founders to offer flexibility without becoming the permanent support desk for every unfamiliar payment request.

FAQs
Should small businesses accept cryptocurrency or other digital-asset payments?
It depends on customer demand, transaction costs, operational capacity, and the business’s ability to manage accounting and compliance requirements. A limited pilot can help determine whether the additional payment option creates enough value to justify its workload.
What should a business document when receiving digital-asset payments?
Records should connect each transaction to its commercial purpose, invoice, approval, relevant quantities, timestamps, fees, and supporting transaction references. Businesses should also retain appropriate valuation and conversion information based on their accounting and tax requirements.
How should a small business handle digital-asset conversions?
Businesses should establish an approved conversion process that identifies the assets involved, the intended destination, the authorized person, and the expected outcome. Each conversion should be documented separately and linked to the original customer payment so that the full transaction can be reconciled.
How can small businesses protect digital-asset payment operations?
Use multi-factor authentication where supported, restrict transaction permissions, and store wallet keys and recovery information securely rather than in shared spreadsheets. Assign clear approval responsibilities and establish a backup process for monitoring transactions and investigating exceptions.
How can a business decide whether to keep a new digital-asset payment option?
Review completed sales, customer demand, processing costs, staff time, reconciliation effort, and unresolved payment issues during a defined pilot period. Continue only if the benefits justify the additional workload and the business can manage the process reliably without constant founder involvement.
Purina Fancy Feast Gravy Lovers Wet Cat Food, 3 oz Cans, 30-Pack | Variety Pack with poultry and beef grilled gourmet recipes, made with no artificial colors or preservatives
$28.06 (as of October 30, 2026 03:14 GMT +00:00 - More infoProduct prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on [relevant Amazon Site(s), as applicable] at the time of purchase will apply to the purchase of this product.)
SKITTLES Original, Wild Berry & STARBURST Fun Size Variety Bag, 20.13 oz | Chewy fruity SKITTLES and STARBURST in fun size packs, great for movie nights, party favors, road trips and Halloween Candy
$9.96 (as of October 30, 2026 03:14 GMT +00:00 - More infoProduct prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on [relevant Amazon Site(s), as applicable] at the time of purchase will apply to the purchase of this product.)
Earth Rated Dog Wipes for Paws & Butt, Deodorizing, Unscented, 100ct | Hypoallergenic, 3-in-1 Cleaning and Hydrating, for Grooming Paws, Body and Butt
$9.99 (as of October 30, 2026 03:14 GMT +00:00 - More infoProduct prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on [relevant Amazon Site(s), as applicable] at the time of purchase will apply to the purchase of this product.)
DEEP DEAR Puppy Pads for Dogs , Large 30x28 in ,100 Count | 6-Layer Leak-Proof Disposable Dog Pee Pads for Potty Training, Quick-Dry Wee Wee Pads for Dogs & Puppies, XL Value Pack
$27.99 (as of October 30, 2026 03:23 GMT +00:00 - More infoProduct prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on [relevant Amazon Site(s), as applicable] at the time of purchase will apply to the purchase of this product.)


Post Comment