
Why KPMG’s Latest Property and Construction Report Could Change How You Invest Forever
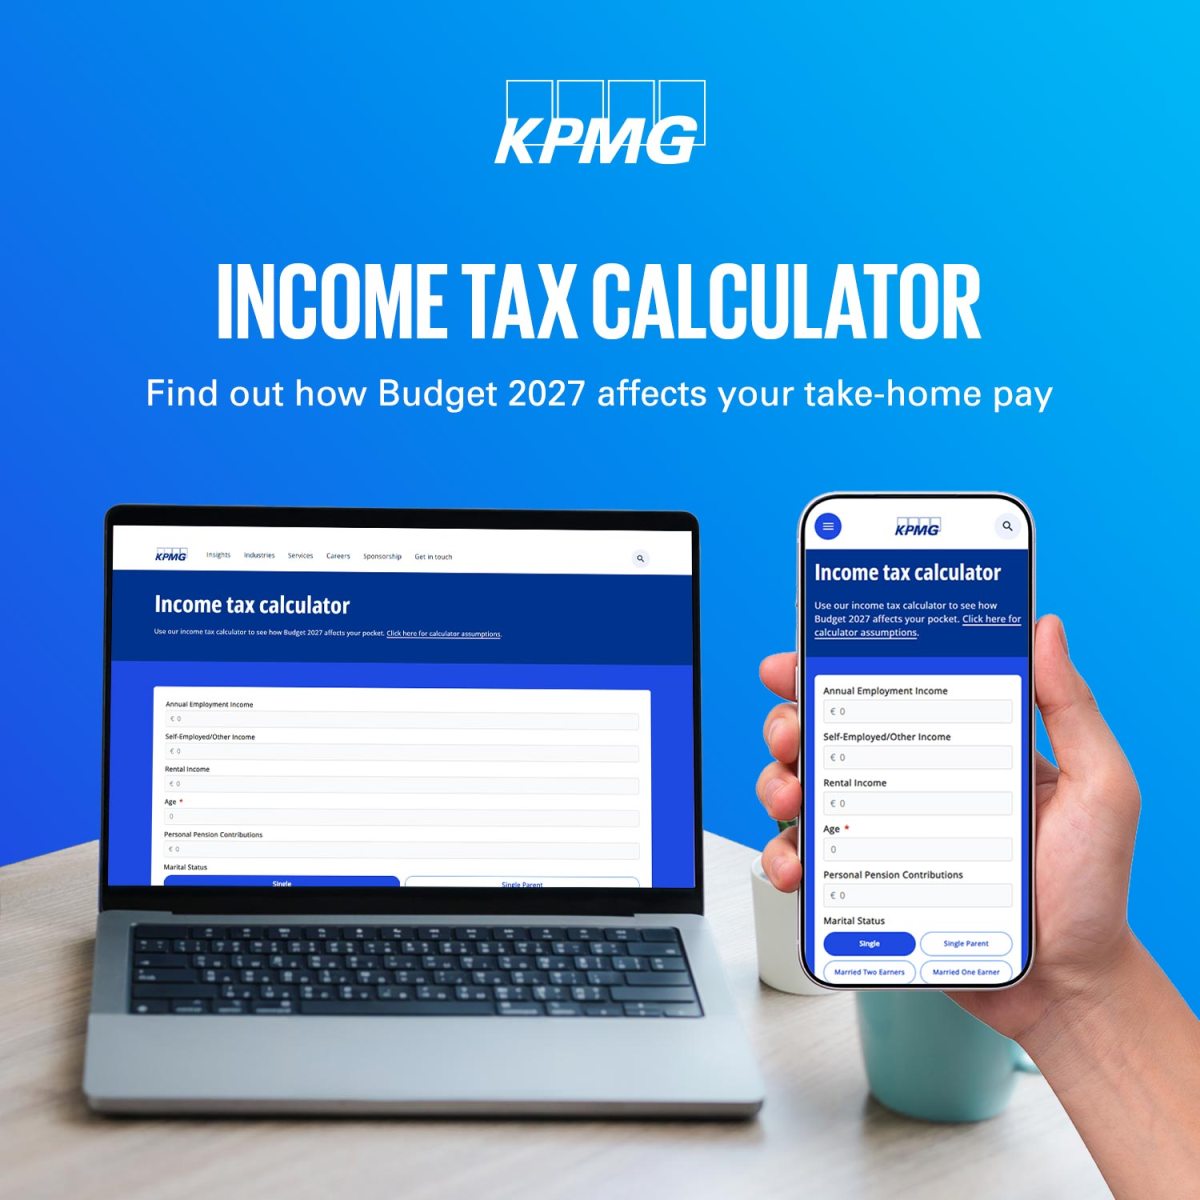
When it comes to juggling the ever-changing landscape of housing and property, Budget 2027 rolls in with a reassuring nod to renters and homeowners alike—offering targeted support that’s both timely and sensible. But here’s the twist: amid a sea of prior tax tweaks and policy shifts, the industry wasn’t exactly caught off guard by the new measures. What’s truly captivating is the continued drive to invest heavily in critical infrastructure—a backbone move that hints at sustainable housing delivery finally gaining some serious traction. Yet, one can’t help but wonder… with macroeconomic storms still looming, will these targeted incentives and policy nudges be enough to spur the supply of lasting, quality homes across Ireland? It’s a fine balancing act, and this budget doesn’t just tip its hat to stability; it challenges policymakers to lean further into solutions that champion not just growth, but the kind of growth that sticks. Dive deeper into what Budget 2027 means for you and the property sector with insights straight from KPMG’s Carmel Logan. LEARN MORE
Budget 2027 provides targeted support for renters and homeowners, alongside a limited number of measures affecting the wider property and construction sector, writes Carmel Logan, Tax Partner, KPMG
This was largely anticipated by the industry, given the backdrop of an extensive suite of tax and non-tax measures introduced in recent years.
We welcome the continued focus on capital investment in critical infrastructure that is key to supporting sustained housing delivery.
While the stability offered by Budget 2027 is welcomed, viability challenges remain given the wider macroeconomic factors, so we encourage Government to continue consideration of targeted incentives and policy changes that increase supply of sustainable stock across all asset classes and tenures.
Key measures
- Derelict Property Tax
A new Derelict Property Tax is to be introduced in the Finance Bill and administered by Revenue. It will apply to residential and non-residential properties identified as derelict by Local Authorities.
A property may be regarded as derelict where it is unused and unsuitable for use as a dwelling, business premises or community facility, including because of significant structural deterioration. The proposed rate is 7% of the property’s self-assessed value. A property may fall outside the charge in the case of remediation of the property, demolition and clearing of derelict structures, or a sale of the property to a purchaser who subsequently addresses the dereliction.
A limited deferral mechanism will be available where remediation is underway. The tax will be introduced on a phased basis, initially applying to towns and cities with populations of 4,000 or more from 2027, before expanding to towns of 2,000 or more residents from 2028. A total of 107 towns will be in scope in the first year, increasing to 171 in the second year.
Preliminary registers will be published by Local Authorities on 1 September 2027, with final registers to be published on 1 March 2028. The first filing and payment deadline will be 23 June 2028.
- Capital gains tax on development land
The 33% capital gains tax rate will continue to apply to disposals of development land, despite the wider reduction in the general capital gains tax rate to 31%.

- Rent tax credit
The credit will increase by €150 to €1,150 for an individual and €2,300 for a jointly assessed couple. The increased amounts will apply for the 2027 and 2028 tax years.
- Help-to-Buy
The maximum refund under the Help-to-Buy scheme will increase by €5,000, from €30,000 to €35,000, from 7 October 2026. The other parameters and conditions of the scheme are unchanged.
- Residential Zoned Land Tax
The Finance Bill is expected to provide additional scope for owners of land included on the 2027 Residential Zoned Land Tax map to seek a change in zoning and, in specified circumstances, an exemption. The measure is expected to be similar to the limited rezoning provision introduced by Finance Act 2025.
- Rent-a-Room Relief
The annual relief threshold will increase from €14,000 to €16,000 from 1 January 2027. The relief will also extend to certain newly-installed detached auxiliary dwellings, measuring between 32 and 45 square metres, with retrospective effect from 27 July 2026.
KPMG insights – our view
Housing and related infrastructure remain among the most significant constraints on Ireland’s competitiveness and economic growth. Employers, investors and households all experience the consequences of insufficient supply, high costs and long delivery timelines.
The sector has seen an extensive programme of tax, planning and housing-policy change in recent years. There are positive signs that these measures, taken together, are having an impact on housing delivery.
Recently-published Government data shows a 162% increase in new-home commencements during the first eight months of 2026 compared with the same period in 2025, and a 60% increase in planning permissions for new homes in the second quarter of 2026 compared with the second quarter of 2025.
These figures suggest momentum in housebuilding, but it is vital that we continue to address ongoing challenges faced by the sector and support housing delivery.
Infrastructure developments
Infrastructure is central to that objective, particularly investment in water, energy and transport. We welcome the continued focus on efficient delivery of the €275.4 billion of public capital investment provided for under the National Development Plan for the period from 2026 to 2035, building on the work of the Accelerating Infrastructure Taskforce.
The provision for Local Authorities from 2027 to spend an additional €200m annually from their own resources or through borrowing could also support housing delivery if this additional capacity is directed towards capital projects that unlock viable development.
Help-to-Buy
For renters and first-time buyers, the increases in the rent tax credit and Help-to-Buy refund should provide welcome short-term support. However, demand-side reliefs are most effective when accompanied by sustained additions to housing supply, timely infrastructure and viable development pipelines.
The immediate Help-to-Buy change may also give rise to practical considerations for transactions where, prior to 7 October 2026, a preliminary Help-to-Buy application has been made before contracts have been signed. In order to avoid delays in closing, it will be important to get clear
Revenue guidance confirming that the higher refund is available for contracts signed on or after 7 October 2026, without the need for reapplication.
Derelict Property Tax
The new Derelict Property Tax could help return vacant/unused property to productive use. However, the particular details of the tax and its implementation must be carefully considered in order to protect landowners from being unnecessarily burdened.
Early engagement between the Government, Local Authorities, Revenue, landowners and industry will be important, particularly given the recent experience of operational complexity and practical difficulties during the rollout of Residential Zoned Land Tax.
The decision not to extend the general capital gains tax reduction to development land is difficult to reconcile with the policy objective of encouraging land activation and the transfer of land to parties best-placed to deliver housing. The Government should consider applying the 31% rate to qualifying development land disposals to support land activation.
Residential Zoned Land Tax
The additional rezoning opportunity under the Residential Zoned Land Tax is welcome but is likely to be most relevant to farmers and other owners who do not intend to develop their land.

It does not address the principal concerns arising where development is delayed by factors outside an owner’s or developer’s control, or where deferred tax is clawed back on the sale of land that is actively being developed, including in forward-funding structures.
Targeted amendments could address these issues while preserving the tax’s land-activation objective.
Get in touch
The measures unveiled in Budget 2027 will have far-reaching implications for businesses across Ireland. If you have any enquiries, comments, or wish to explore further, we are here to assist.
Contact Carmel Logan of our Tax team today.
For more insights, visit KPMG

Dr. Elsey's Ultra UnScented Clumping Clay Cat Litter 40 lb. Bag
$21.03 (as of October 7, 2026 03:10 GMT +00:00 - More infoProduct prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on [relevant Amazon Site(s), as applicable] at the time of purchase will apply to the purchase of this product.)
Wonderful Halos Mandarins, Sweet, Seedless, Easy Peel Mandarin Oranges - Healthy Food, Fresh Fruit, 3lb Bag
(as of October 7, 2026 03:07 GMT +00:00 - More infoProduct prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on [relevant Amazon Site(s), as applicable] at the time of purchase will apply to the purchase of this product.)
Amazon Fire TV Stick 4K Max (newest model), streaming device, with AI-powered Fire TV Search, supports Wi-Fi 6E, free & live TV without cable or satellite, find shows faster with Alexa+
$44.99 (as of October 7, 2026 03:20 GMT +00:00 - More infoProduct prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on [relevant Amazon Site(s), as applicable] at the time of purchase will apply to the purchase of this product.)
Earth Rated Dog Poop Bags on Refill Rolls, 270 Bags, Lavender | Guaranteed Leak Proof and Extra Thick Waste Bag Refill Rolls
$12.74 (as of October 7, 2026 03:10 GMT +00:00 - More infoProduct prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on [relevant Amazon Site(s), as applicable] at the time of purchase will apply to the purchase of this product.)

Post Comment