
Why Your Cash Flow Crisis Is a Lie—and the Real Profit Killer Hiding in Plain Sight
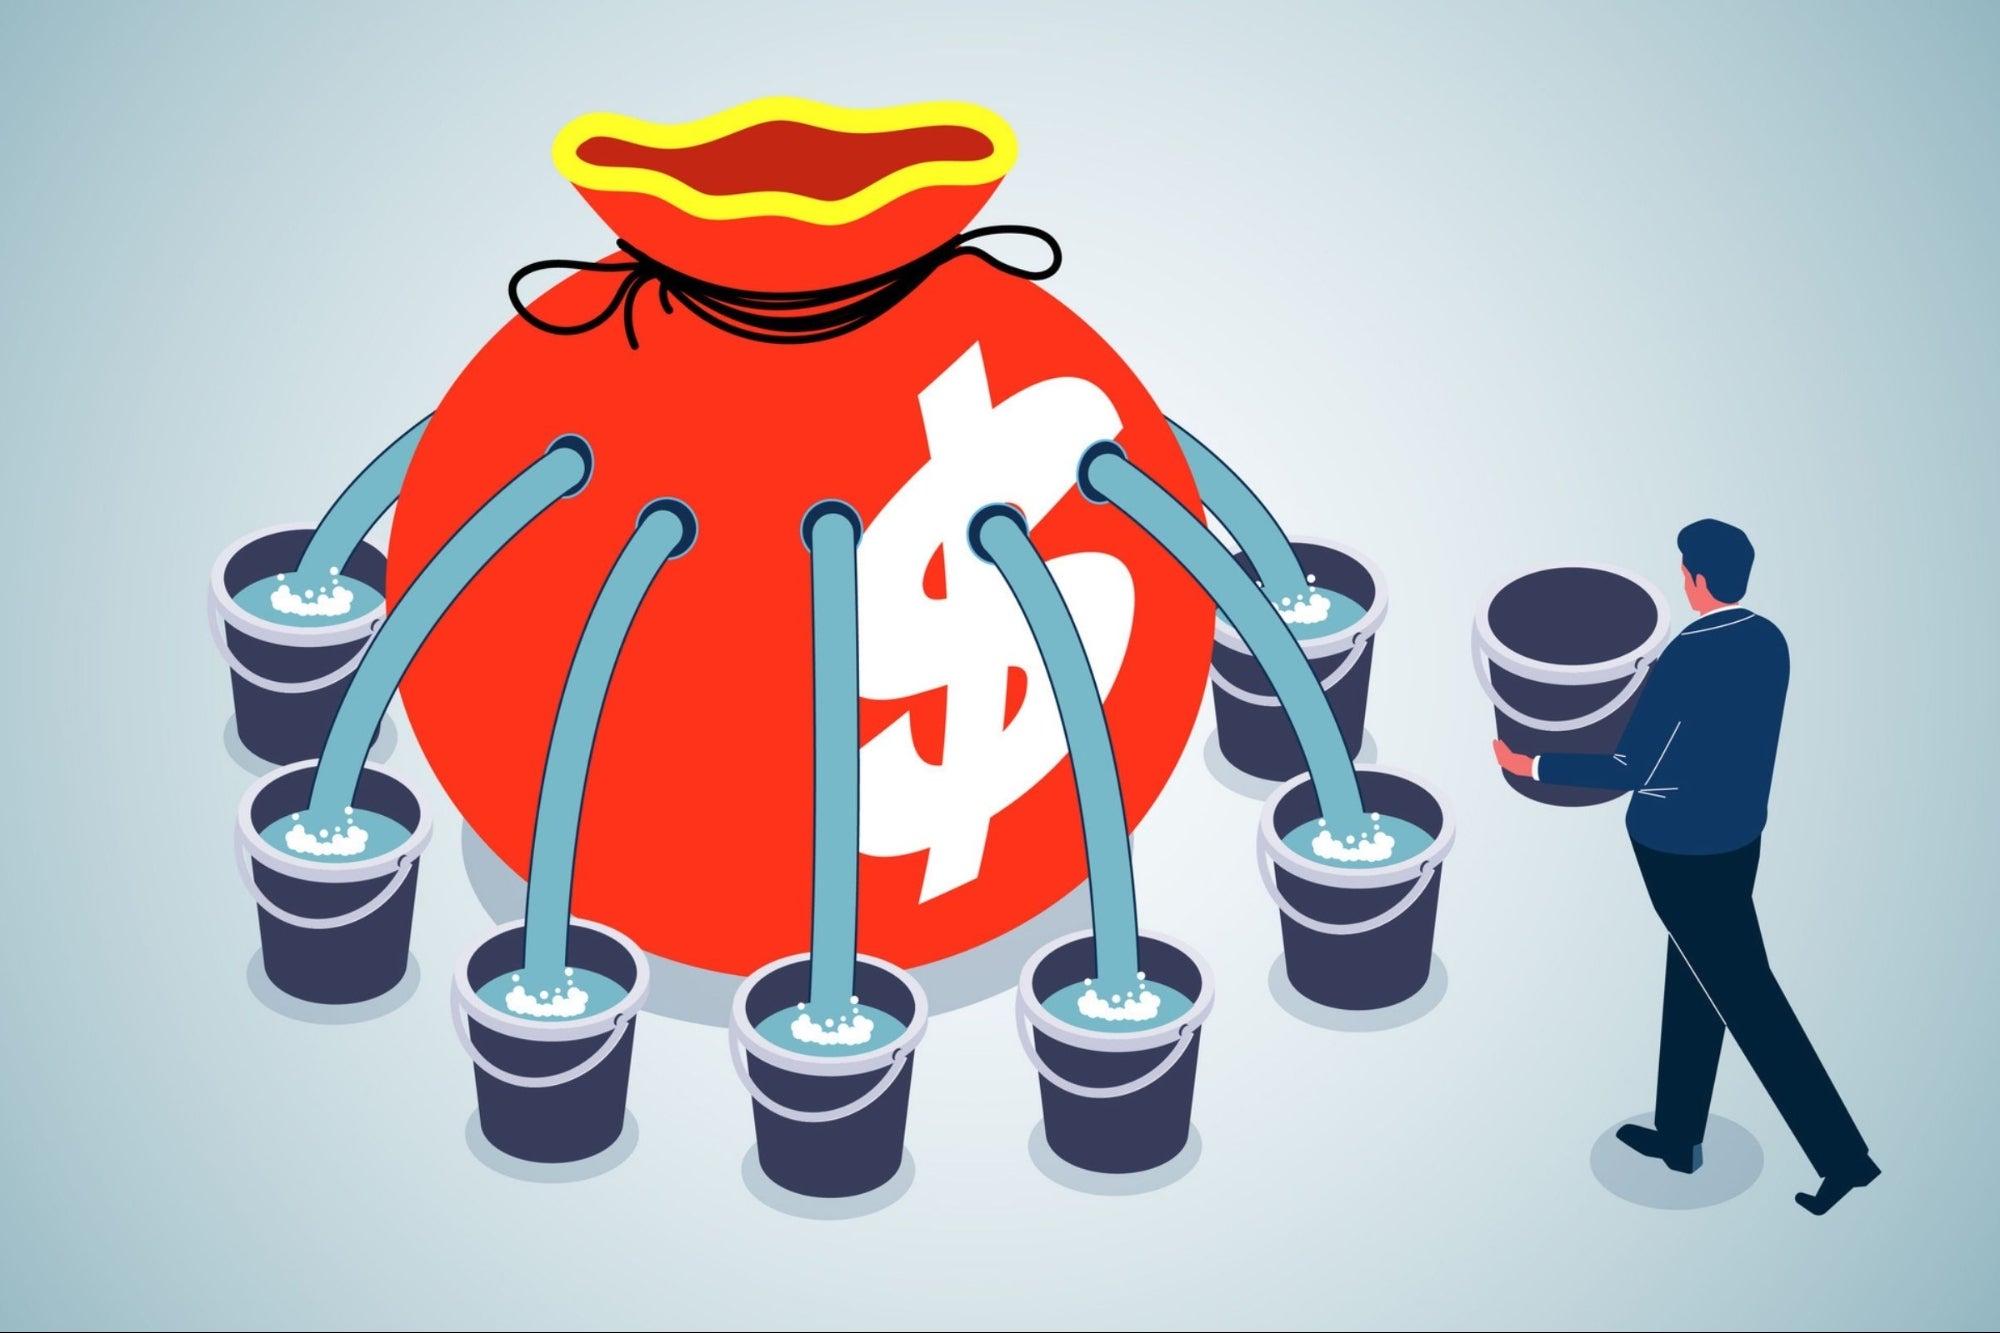
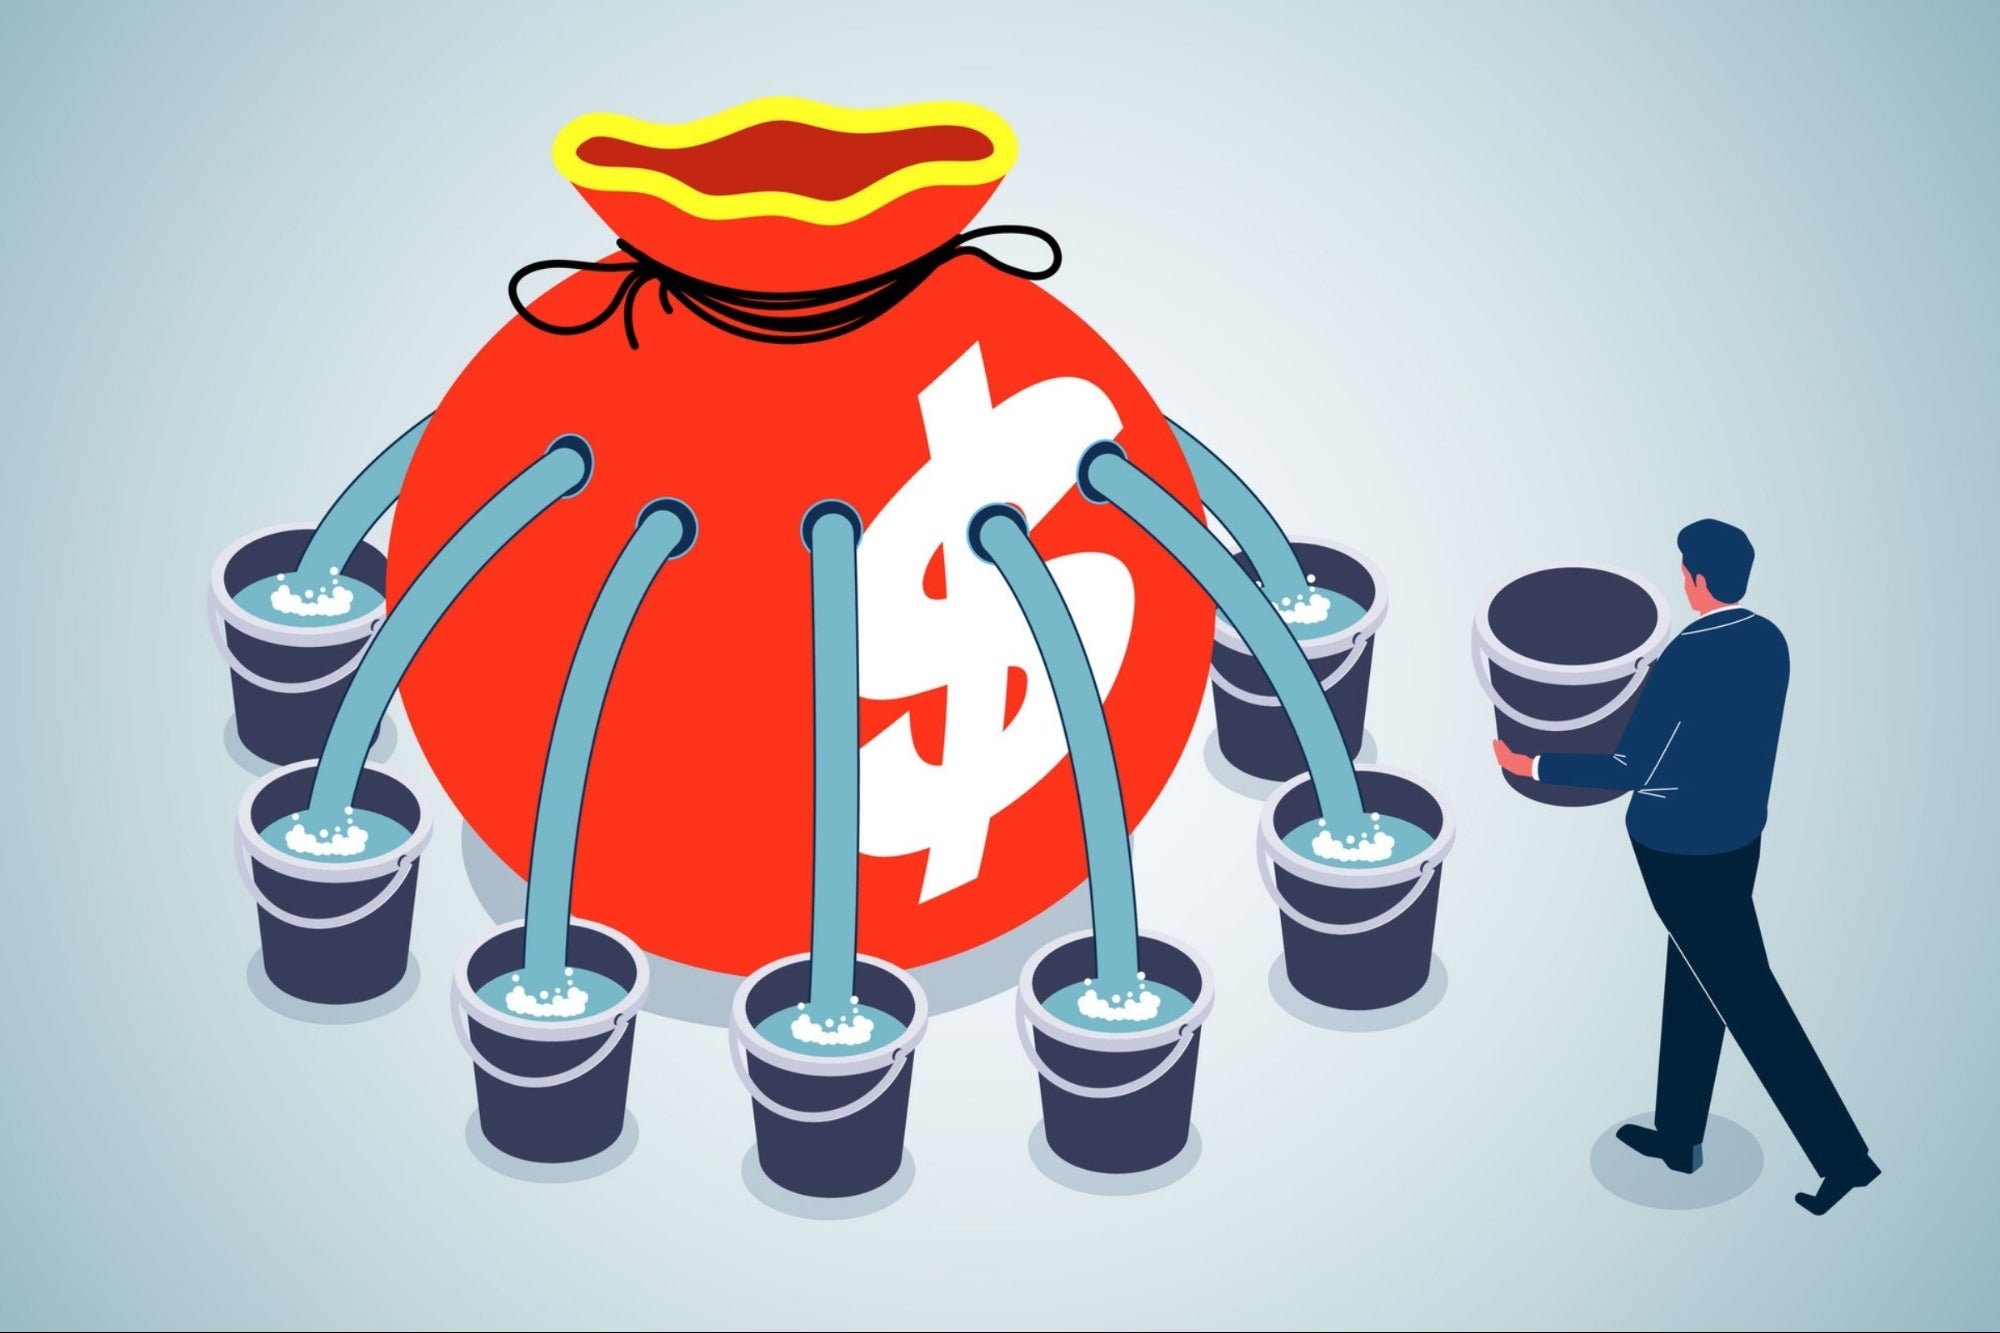
Ever stared at your business bank balance and wondered, “What’s really going on here?” It’s tempting to slap on a bandaid — maybe chase a few quick sales, apply for a loan, or hold off on some bills — but that’s like putting a sink plug in a boat with a gaping hole. Take Virginia’s story: four years in business, yet her company never saw a positive operating cash flow. Shocking, right? But here’s the kicker: labeling it a “cash flow problem” barely scratches the surface. It’s like diagnosing a cough without checking if it’s a cold, allergies, or something more serious. Your cash flow isn’t the enemy; it’s the messenger trying to tell you something critical. Instead of rushing to patch up symptoms, shouldn’t we be asking the deeper question—what is my cash flow really trying to say? Let’s dive into how understanding these financial whispers can save your business from sinking before you even realize it’s taking on water. LEARN MORE
Opinions expressed by Entrepreneur contributors are their own.
Key Takeaways
- A shrinking bank balance is a symptom, not the disease, so figure out what’s causing it before you try to fix it.
- Financing can buy you time, but it can’t repair a broken pricing model, bloated overhead or slow collections.
A few months after I started working with an entrepreneur I’ll call Virginia, I discovered something in her financials that stopped me cold. Her company had been operating for four years, and during that entire time, it had never generated positive operating cash flow.
Virginia didn’t seem to know that until I told her. The business had been borrowing money to keep itself running, and by the time I came in, the balance sheet was carrying significant debt. Then the pressure got worse. Within six months, the company lost roughly $750,000 in corporate sponsorship as funding for diversity, equity and inclusion initiatives dried up.
From the outside, you could have called this a cash flow problem. That description wouldn’t have told us much. I needed to understand what had been happening inside the business for years before the cash crunch became impossible to ignore. That meant digging into the financials and asking a more useful question: What was the cash flow trying to tell us?
If you’ve ever gone to a doctor because you weren’t feeling well, you know the first conversation is about diagnosis. A headache can have dozens of different causes, and prescribing medication before understanding the underlying issue may provide temporary relief without solving the real problem. Cash flow works much the same way. The bank balance tells you something is wrong. Your job as the business owner is to figure out why.
That’s why I encourage entrepreneurs to stop asking, “How do I improve cash flow?” and start asking a different question: “What is my cash flow trying to tell me?”
Cash flow is trying to tell you something
One of the biggest mistakes entrepreneurs make is treating cash flow as a problem all by itself. When the bank balance starts shrinking, the instinct is to find more cash as quickly as possible. Sometimes that means chasing more sales. Other times, it means delaying expenses or applying for financing. Those decisions may relieve the immediate pressure, but they don’t always address the underlying issue.
Think about your own business for a moment. Has cash become tight because customers are taking longer to pay? Have payroll costs grown faster than revenue? Are your prices keeping pace with rising expenses? Have you hired ahead of demand, or has inventory tied up more cash than expected? Every one of those situations creates cash flow pressure, yet each one requires a different solution.
Your responsibility as the owner isn’t simply finding more cash. It’s understanding why the cash isn’t there in the first place.
Learn to read the symptoms
When cash becomes tight, entrepreneurs naturally focus on the immediate problem because payroll is approaching, vendors expect to be paid and daily operations must continue. Under that kind of pressure, it’s easy to reach for the fastest solution instead of the right one.
I’ve found that a better question changes the entire conversation. Ask yourself: “Is cash tight because of when money comes in and goes out, or because the business isn’t generating enough profit on the work we’re doing?” That question forces you to look beyond the bank balance. You may have a timing problem between expenses and collections, or you may have a deeper issue with pricing, margins or the business model itself.
Your financial statements usually provide the answers. The income statement reveals if margins have quietly eroded because expenses are growing faster than revenue. The balance sheet shows if customers are taking longer to pay or if inventory is consuming more cash than it should. The cash flow statement explains where money is actually moving throughout the business. Together, those reports tell a story that’s impossible to see by looking at the bank balance alone.
Financing isn’t always the cure
There are times when financing makes perfect sense. Healthy businesses sometimes need additional working capital to support growth, purchase equipment or navigate seasonal fluctuations. Used strategically, financing creates flexibility and allows a company to invest with confidence.
Financing can also hide deeper problems. Imagine a business with shrinking profit margins because prices haven’t kept pace with rising costs. A line of credit may relieve immediate pressure, but it doesn’t solve the pricing issue. The company continues losing money on every sale while taking on additional debt. The same pattern appears when cash flow problems stem from excessive overhead, weak collections or inefficient operations. Financing buys time, but it doesn’t repair the underlying condition.
Doctors don’t prescribe treatment until they’ve identified the illness. Entrepreneurs shouldn’t make major financial decisions until they’ve diagnosed the source of their cash-flow pressure.
Your financial statements are diagnostic tools
Entrepreneurs sometimes think of financial statements as documents prepared for lenders, accountants or tax returns. I’ve always viewed them differently because they reveal a business’s health long before problems become obvious.
Just as physicians rely on tests before recommending treatment, business owners should rely on accurate financial information before making important decisions. Your income statement explains how profit is being generated. Your balance sheet shows the company’s financial strength and highlights issues that may not appear in the bank account. Your cash flow statement tracks how money moves through the business. Together, those reports help explain why cash is tight rather than simply confirming it.
That’s one of the reasons I believe financial literacy is a core leadership skill. Entrepreneurs who understand their numbers spend less time reacting to symptoms and more time solving the problems creating those symptoms.
Diagnose before you prescribe
One of the patterns I’ve seen throughout my career is that entrepreneurs become remarkably effective problem-solvers once they understand the real issue. The challenge is that many businesses begin treating symptoms before they’ve identified the cause. That approach provides temporary relief while allowing the underlying problem to continue to grow.
The next time you find yourself saying, “We have a cash flow problem,” pause before deciding what to do next. Ask yourself what your cash flow is trying to tell you. The answer may point to pricing, staffing, operations, slower collections or a business model that no longer produces healthy margins.
Just like good medicine begins with an accurate diagnosis, healthy businesses begin with understanding what the numbers are trying to say. When you learn to identify the root cause rather than react to symptoms, you put yourself in a position to solve the right problem and build a stronger business for the future.
Key Takeaways
- A shrinking bank balance is a symptom, not the disease, so figure out what’s causing it before you try to fix it.
- Financing can buy you time, but it can’t repair a broken pricing model, bloated overhead or slow collections.
A few months after I started working with an entrepreneur I’ll call Virginia, I discovered something in her financials that stopped me cold. Her company had been operating for four years, and during that entire time, it had never generated positive operating cash flow.
Virginia didn’t seem to know that until I told her. The business had been borrowing money to keep itself running, and by the time I came in, the balance sheet was carrying significant debt. Then the pressure got worse. Within six months, the company lost roughly $750,000 in corporate sponsorship as funding for diversity, equity and inclusion initiatives dried up.
From the outside, you could have called this a cash flow problem. That description wouldn’t have told us much. I needed to understand what had been happening inside the business for years before the cash crunch became impossible to ignore. That meant digging into the financials and asking a more useful question: What was the cash flow trying to tell us?
blink plus plan with monthly auto-renewal
$11.99 (as of October 22, 2026 03:23 GMT +00:00 - More infoProduct prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on [relevant Amazon Site(s), as applicable] at the time of purchase will apply to the purchase of this product.)
Amazon Fire TV Stick HD (newest model), free & live TV, Alexa Voice Remote, powered by the TV, effortless setup, find shows faster with Alexa+
$19.99 (as of October 22, 2026 03:23 GMT +00:00 - More infoProduct prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on [relevant Amazon Site(s), as applicable] at the time of purchase will apply to the purchase of this product.)
Petcarex Dog Dental Powder, Dog Teeth Cleaning Breath Freshener | Pet Tartar and Plaque Remover for Teeth, Tooth Cleaning Powder with Probiotics for Dogs of All Breeds, Duck Flavor
$24.99 (as of October 22, 2026 03:22 GMT +00:00 - More infoProduct prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on [relevant Amazon Site(s), as applicable] at the time of purchase will apply to the purchase of this product.)
Alex Tech 10ft - 1/2 inch Cord Protector Wire Loom Tubing Cable Sleeve Split Sleeving For USB Cable Power Cord Audio Video Cable – Protect Cat From Chewing - Black
$8.99 (as of October 22, 2026 03:23 GMT +00:00 - More infoProduct prices and availability are accurate as of the date/time indicated and are subject to change. Any price and availability information displayed on [relevant Amazon Site(s), as applicable] at the time of purchase will apply to the purchase of this product.)

Post Comment